CBA Hypomonitor: September Stabilization at a Higher-than-Normal Rate of 5.1%
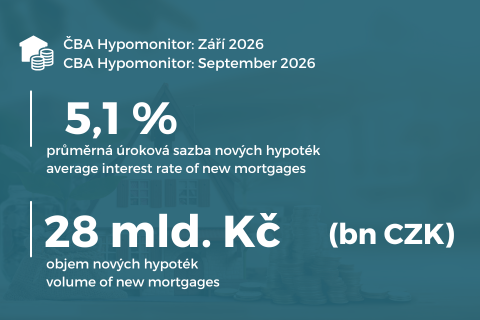
Prague, October 14, 2026 – In September, banks and building societies issued 28 billion CZK in new mortgages (excluding refinancing). Compared to August, the volume increased by 5%, even though in recent years it has typically declined month-over-month in September. The seasonally adjusted volume thus rose by 11% to nearly 30 billion CZK, exceeding the average of the previous three months. Since the beginning of the year, the volume of new mortgages has reached 301.4 billion CZK, which is approximately 66 billion more than a year ago. The average interest rate on new mortgages rose only slightly to 5.1% from 5.0% in August, due to a further narrowing of the spread relative to market interest rates. This information is based on data from the CBA Hypomonitor, which tracks data from all domestic banks and building societies providing mortgage loans.
The September data show stabilization at a higher-than-normal level following the August cooling of the mortgage market after the spring rush to secure loans. Some clients took out mortgages earlier in an effort to avoid the impact of higher market rates as well as the CNB’s April tightening of rules for so-called investment mortgages. The seasonally adjusted average number of new mortgages in September approached the long-term average of over 6,400 per month. The average amount of a new mortgage increased by just under 80,000 to 4.67 million CZK, which, at an interest rate of 5.1%, raises the illustrative average monthly payment on a new mortgage to roughly 26,500 CZK, but for half of all new mortgages, it amounts to 21,300 korunas.
These mortgage figures should support the central bank’s wait-and-see approach, even as it adjusts its macroprudential policy for mortgages on November 26. More on this in the CBA Monitor.
Table 1: Summary of Mortgage Volume and Average Interest Rates for September 2026
| monthly figures |
| ytd data | ||||
| Volume | Number | Rate |
| Volume | Number | Rate |
|
| ||||||
Total | 35,4 | 7 942 | 5,09 |
| 404,4 | 90 317 | 4,66 |
New loans | 28,0 | 5 995 | 5,10 |
| 301,4 | 64 046 | 4,69 |
of which: |
|
|
|
|
|
|
|
for the purchase | 22,3 | 4 658 | 5,10 |
| 218,9 | 46 426 | 4,69 |
for reconstruction | 4,5 | 962 | 5,00 |
| 49,5 | 10 555 | 4,62 |
other | 1,2 | 375 | 5,40 |
| 33,0 | 7 065 | 4,75 |
Refinanced from another institution | 6,4 | 1 661 | 5,05 |
| 87,5 | 22 449 | 4,58 |
Refinanced internally, increased | 1,1 | 286 | 5,08 |
| 15,6 | 3 822 | 4,62 |
Source: CBA Hypomonitor. Note: Seasonally unadjusted data
Jaromír Šindel, Chief Economist of the Czech Banking Association:“In September, the mortgage market approached its long-term norm in terms of the number of new mortgages. This was despite—or rather, due to—the continued modest rise in the actual mortgage interest rate. In September, this rate again only partially alleviated the pressure from higher market interest rates, reaching 5.1%. Higher market interest rates will likely continue to put pressure on the mortgage market. The declining share of refinancing suggests that borrowers stockpiled refinancing in the spring, even for loans with expiring fixed-rate periods.”

Note: The outlook through the end of the year is indicative—it is based on the current trend, not on a model prediction. For the remainder of the year, it assumes a 7% adjustment in the number of mortgages relative to the pace recorded in the second half of 2025. See Chart 7 for an illustration.

September saw activity stabilize at a level slightly above normal; seasonally adjusted activity slightly exceeded the summer average
Overall, banks and building societies reported new and refinanced mortgages totaling CZK 35.4 billion in September. This is 2.8% more than in August, but 6% less year-over-year. Since the beginning of the year, the total volume has reached CZK 404.4 billion, representing a 38% increase compared to the same period last year.
In September, new mortgage loans (excluding refinancing) totaled CZK 28 billion. Compared to August, new mortgage activity increased by approximately 5% in volume. This is a more favorable result than typical seasonal trends would suggest. After seasonal adjustment, the volume increased by 11% to CZK 29.6 billion from CZK 26.7 billion in August and exceeded the average of the previous three months, which was CZK 28.7 billion. Compared to the second half of last year, September’s volume was approximately 1% higher. Year-over-year, it rose by 5%, so the market remains strong, although growth is significantly more moderate than the 41% increase seen during 2025.
Vilém Mádr, Product Manager at Česká spořitelna:“After a period of dynamic growth, the Czech real estate market is experiencing a slight cooling in demand for investment properties. The main challenge when purchasing real estate at present is the combination of high prices and high interest rates, which, due to the volatile interbank market, remain at their all-time highs. To bridge this situation, clients now have the option of a shorter, for example, two-year fixed-rate period. This can give clients time for the market to stabilize and to prepare for a future decline in borrowing costs when the rate is subsequently reset.”
The number of new mortgages rose by 2.9% month-over-month in September to 5,995, but remained 12% lower year-over-year. After seasonal adjustment, we estimate approximately 6,395 new loans, which is roughly 1% above the average of the previous three months. Since the beginning of the year, 64,000 new mortgages have been granted, 13% more than a year ago. The pace of the last three months implies approximately 82,500 mortgages for the entire year, which is slightly higher than the more conservative estimate, which assumes a 7% correction in the final quarter compared to the second half of 2025. That projection points to roughly 82,000, or about 8% more than last year. The result would nevertheless remain below the 92,000 recorded from 2016 to 2018 and below the 114,000 from 2021.
Chart 2: Newly Granted Mortgages (Excluding Refinancing
) September saw a slight recovery in both the volume and number of new mortgages, returning them to the stronger levels seen in recent months …

Source: Czech Banking Association, CNB, CZSO, Flat Zone.
Chart 3: Average Mortgage Amount by Purpose
… at the same time, the average amount of a new mortgage rose slightly to 4.67 million CZK.

Source: CNB, CBA Hypomonitor
The volume of refinanced and increased loans reached 7.5 billion CZK in September. This was 6% above the 2025 average and 91% above the 2024 average. The share of refinancing in the total volume fell to 21.1%, having reached 27% in February and June. In September, it was thus close to last year’s average. However, it remains above the 17.2% share recorded in 2022–2023, but below the nearly 29% share recorded in 2020–2021. The average rate on refinanced mortgages in September was 5.05%, 0.55 percentage points higher than a year ago.
If the share of external refinancing among maturing fixed-rate mortgages remained unchanged, this suggests a certain degree of “stockpiling” of lower interest rates even for this year’s maturing fixed-rate mortgages. The increased volume of refinancing reflects a combination of longer-term fixed-rate periods from a time of exceptionally low rates and shorter-term fixed-rate periods from the recent period of higher borrowing costs. For some households, this refinancing means a noticeable increase in monthly payments; conversely, for loans taken out in 2023 with a mortgage interest rate of 5.82%, it may bring some relief.
Jan Fajfr, Head of Loan Products in Fio Bank’s Client Division:“Banks’ willingness to accommodate clients and offer them more favorable terms—even at the cost of low margins, that is, at the expense of their own short-term business interests—is also playing an important role in the mortgage market right now. Households must carefully consider the loan amount, their ability to afford the monthly payment, and the length of the fixed-rate period. The decision to opt for a shorter fixed-rate period should not be based solely on expectations of an imminent drop in interest rates, but primarily on the household’s ability to cope with less favorable market conditions.”
The average mortgage rate rose to 5.1%, thereby only partially alleviating the pressure from higher market interest rates
The average interest rate on new mortgages rose further in September to 5.1% from 5.0% in August. It was thus 0.58 percentage points higher than a year ago. The mortgage interest rate reached its recent low in March of this year at 4.43%, following a shift in thinking regarding the future direction of monetary policy. For a mortgage at the current average amount, this year-over-year rate increase raises the illustrative monthly payment by approximately 1,500 CZK, or about 1.5% of the applicant’s net income. By comparison, the average rate in 2025 was 4.58%, and in 2024 it reached 5.07%.
The September mortgage rate was 0.31 percentage points above the September average of relevant market swap rates. The spread thus narrowed compared with the previous three months and remained well below the long-term average of around one percentage point. Banks have so far reflected the rise in the market cost of money in their client rates only gradually; however, the September and October rise in interest rate swaps is creating further pressure on mortgage rates. In our study, we highlighted structural factors—primarily the strength of demand in a competitive market—that influence the pass-through of market rates to mortgage rates. A new survey, however, suggests that in the third quarter there may be a lack of momentum to keep mortgage rates significantly below market swap rates. For more details, see here: Mortgage standards have tightened, but strong demand was not the only factor dampening the impact on lending conditions.
Czech longer-term market interest rates,[1] which have a key influence on mortgage rates—where three-year fixed-rate terms predominate—remained on an upward trend in September and the first half of October, primarily due to the deteriorating situation in the oil market, but also supported by domestic factors. Despite the CNB keeping its benchmark interest rate unchanged at 3.75%, Czech five-year interest rate swaps rose by 0.35 percentage points in September to an average of 4.85% from 4.50% in August. This marked the highest monthly average in the past twelve months and was 1.2 percentage points above the 2025 average. U.S. and euro-denominated five-year swaps also rose. Higher foreign rates, more expensive energy, and concerns about a renewed intensification of inflationary pressures are thus keeping the long-term cost of capital at an elevated level. Among the domestic factors putting upward pressure on market interest rates—which anticipate another CNB rate hike—is the persistently strong 3.1% year-over-year growth in core inflation recorded in September.
[1]These are primarily long-term interest rate swaps (IRS), which reflect the cost of capital over longer maturities—in recent years, around 3 to 5 years, but more recently around 3 years. Alternatively, shorter-term fixed-rate periods are used, while 10-year maturities are less relevant due to higher central bank rates compared to the previous decade, as well as due to the costs incurred when prepaying mortgages.
Chart 4: Average Mortgage Interest Rate – New Loans
The September mortgage rate continued to reflect the previous rise in the market price of money

Source: CNB, CBA Hypomonitor
Chart 5: Renewed U.S. attacks on Iran are keeping market swap rates higher
… which gained further upward momentum in September, reaching levels seen in the second half of 2023

Source: Macrobond (October 12, 2026), CBA
The average monthly payment rose to approximately 26,500 CZK, with a median of 21,300
The combination of rising interest rates and higher average mortgage amounts in September 2026, compared with the average values from 2025, increased the average monthly payment on newly issued mortgages by 3,900 CZK. Table 2 illustrates scenarios for the development of monthly payments for various mortgage terms. The table suggests that a rise in mortgage rates of more than 0.5 percentage points from their 2025 average of 4.58% resulted, for an average mortgage size with a typical repayment term of approximately 27 years, an increase in the monthly payment of just under 1,400 CZK to approximately 26,500 CZK—that is, 1.3% of the applicant’s net income compared to last year’s average payment. Compared to the average mortgage rate of 5.07% in 2024, the change due to the interest rate was minimal.
However, the current average mortgage amount was 11% higher than its average amount in 2025, which contributes to an increase in the monthly payment of 2,600 CZK compared to last year’s average monthly payment—based on last year’s average mortgage amount but at the current interest rate. The monthly payment on a one-million-koruna mortgage with a 30-year term is around 5,400 CZK at current interest rates.
The impact of interest rates on expiring fixed-rate periods varies in terms of mortgage trends, depending on the year in which the interest rate was fixed. Illustrative examples? Compared to the average 2.33% mortgage interest rate for new mortgages in 2021, the current refinancing rate of 5.05% —when the loan term is shortened—increases the monthly payment on an average mortgage by nearly 3,900 CZK, or about 7.5% of the current average gross wage. However, that wage has increased by 34% compared to the end of 2021. Conversely, the current interest rate would reduce the monthly payment on a 2023 mortgage with an interest rate of 5.82% by about 1,300 korunas. In 2027, mortgage refinancing from 2024 with an interest rate of 5.11% will dominate, with the current interest rate level providing relief of approximately 81 koruna. We discussed the impacts and circumstances in Fokus CBA: The wave of mortgage refinancing is gaining momentum, but the interest rate shock is subsiding. Higher inflation remains a risk.
Table 2: Illustration of Monthly Payments for an Average and Median Mortgage Based on Loan Term and Interest Rate

Source: CBA (the table with values is available in an XLS file attached to this report). Note: The colored column corresponds to the interest rate from the latest CBA Hypomonitor report combined with the typical repayment term; other rates are for illustrative purposes only. The colored row corresponds to the average and median maturities of new mortgages according to CNB data; amounts are rounded to the nearest ten crowns. The median monthly payment is based on the median mortgage amount. This is calculated based on the ratio of the average to the median amount of new mortgage loans over the last three quarters, according to CNB statistics (118.7%). The calculation also assumes an average maturity of 30 years (corresponding to the median) and an average interest rate, since the difference between the average and median rates has been negligible over the long term (approximately 0.045 percentage points). Unlike the average, the median represents a “typical” value—half of the loans are lower and half are higher—and is not influenced by outliers.
The average amount of a new mortgage rose to 4.67 million CZK in September
The average size of new mortgages in September rose by nearly 2% to 4.67 million CZK and was 7% higher than a year ago. The higher average mortgage size at the beginning of this year—when it reached CZK 4.85 million between March and May—likely reflected the lingering effect of pre-stockpiling for so-called investment mortgages. For these, the CNB tightened requirements starting in April, specifically setting the LTV at 70% and the DTI at seven times annual income. Based on CNB data from the Financial Stability Report, we estimate that the average amount of an investment mortgage— i.e., mortgages for additional owner-occupied housing or rental properties, was roughly 29% higher last year and in the first quarter of this year than for owner-occupied mortgages and other truly new mortgages.
The average mortgage amount is also closely linked to trends in real estate prices. In the second quarter, year-over-year growth in these prices slowed only slightly to 8.6%. In the second quarter, the growth in asking prices for apartments slowed to 1.4% quarter-over-quarter from 2.7% in the first quarter, falling below their long-term average increase of 1.8%. However, the growth in actual sales prices remained at 2.5% quarter-over-quarter, signaling a possible future slowdown to 10% year-over-year from 12.3% in the second quarter. According to data from Flat Zone, the transaction price of apartments sold in the second quarter rose to nearly 100,000 crowns per square meter, exceeding 165,000 in Prague. This is 8.3% and 9.7% higher, respectively, than a year ago (see charts on CBA Monitor). However, a more significant slowdown in price growth will continue to be held back by a combination of supply-side constraints and stronger mortgage pre-stockpiling, as well as still-solid real household wages (4.3% year-over-year in Q2-2026; see chart here) and disposable income.
Chart 6: Illustrative comparison of monthly payments for the current average newly issued mortgage versus the same period a year ago, based on the interest rate, mortgage amount, and loan term in years
Year-over-year, the rise in mortgage rates led to an increase in the average monthly payment of 1,000 CZK, while the rise in the average mortgage amount caused an increase of 1,750 CZK. However, the average mortgage amount has been declining over the past two months, which has offset the impact of higher interest rates.

Source: CBA.
Note: Amounts are rounded to the nearest ten crowns.
Statistical Appendix
Chart 7: Seasonality of New Mortgage Loans

Source: CBA Hypomonitor
Note: These are truly new mortgages (i.e., excluding refinancing and loan increases). The underlying data are available in an XLS file attached to the CBA Hypomonitor website. The outlook through the end of the year (fcst) is based on current conditions—it reflects the current trend rather than a model-based forecast. However, for the remainder of the year, it assumes a 7% adjustment in the number of mortgages relative to H2-2025.
Chart 8: Breakdown of New Mortgage Loans by Purpose

Source: CBA Hypomonitor
Note: The latest figure represents the average for the past 12 months. The interpretation of the “other” segment may be skewed by the inclusion of so-called “mortgages without real estate” arranged without a specific purpose. For more details, see the methodological note below.
In 2025, the mortgage market saw strong growth in volume—up 41%—and an increase of nearly a quarter in the number of loans
Throughout 2025, banks and building societies provided new mortgage loans totaling 321 billion CZK. That is 93 billion CZK more than the 228 billion CZK recorded in 2024. This year-over-year jump represents a 41% increase. In addition, mortgages totaling 85 billion CZK were refinanced, bringing the total mortgage market to 406 billion CZK in 2025, up from 275 billion in 2024. If we adjust the volumes for the rise in apartment prices of around 15–16% (according to various statistics), the volume of new mortgages increased by slightly less in real terms. This also corresponds to a more moderate increase in the number of new mortgages in 2025—by just under a quarter to more than 76,110—and a nearly 15% increase in the average amount of new mortgages granted to CZK 4.21 million.
New mortgages in 2025 were financed at an average interest rate of 4.58%, which was half a percentage point lower than in 2024, while the spread relative to the market swap yield curve reached just under one percentage point, slightly below the long-term average. The average monthly mortgage payment in 2025 was just under 22,800 CZK, which is 8.6% more than in 2024, and slightly exceeded last year’s increase in the average nominal wage, which was likely more than 7%. The average year-over-year increase in the monthly mortgage payment of approximately 1,800 korunas in 2025 primarily reflected a higher average mortgage amount, with an increase in the payment of nearly 2,900 korunas, while the lower mortgage interest rate reduced the average monthly payment by more than 1,200 CZK.
Chart 9: Annual Volume, Number, and Average Amount of Mortgages Granted from 2020 to 2025

Source: CBA Hypomonitor
The Czech Banking Association Publishes Aggregate Statistics for the Entire Banking Market
The Czech Banking Association, in cooperation with its member banks, publishes new summary statistics on the housing market. These primarily include the volumes and numbers of newly issued and refinanced mortgages, as well as the corresponding interest rates. The CBA publishes these statistics in aggregated form for the entire banking sector on a regular basis, typically around the middle of each month. All domestic banks and building societies providing mortgages in the Czech Republic participate in the survey. The data is available starting in January 2020 in the attached file at www.cbaonline.cz, where the relevant statistics can also be found separately for banks and building societies. The figures listed above apply to the sector as a whole and can also be viewed in a simple graphical format on the website cbamonitor.cz.
CBA Hypomonitor Methodology
The CBA Hypomonitor classifies mortgage loans provided by banks and building societies to households into several categories in order to distinguish new loans from refinanced loans or internal rate adjustments. New loans are then reported in categories based on the purpose of the loan:
1. New Loans
These are loans whose entire amount enters the economy for the first time. Loan consolidation or refinancing does not fall into this category. They are divided into three categories:
· Purchase of real estate
· Real estate construction—including real estate renovation
· Other new agreements—only new loans that are in no way related to the purchase or construction of real estate (which does not apply in the case of so-called “mortgages without real estate” arranged without a specific purpose), i.e., for example, so-called “American mortgages,” settlement of joint marital property, reimbursement of the purchase price, settlement of an inheritance share, settlement of a cooperative share, etc.
2. Refinanced loans from another financial institution
These are loans created by refinancing one or more loans from a financial institution other than the reporting one. Regardless of the amount refinanced and regardless of the amount of any increase, the total amount of the newly created loan is reported in this category.
3. Increased or internally refinanced loans
These are loans that were already part of the reporting entity’s portfolio in the previous reporting period and for which one of the following changes occurred during the reporting period:
· an increase in the agreed amount
· changes occurred such that the original loan was refinanced or converted into a new loan within the reporting entity. This constitutes a truly new contract, not, for example, merely a new arrangement as part of the refixing of an existing contract. Therefore, the volume of such loans in the CBA statistics is lower than that of “other new arrangements” in the Czech National Bank’s statistics.
Data for the CBA Hypomonitor are provided by the following banks and building societies: Air Bank, Česká spořitelna, ČSOB, ČSOB Stavební spořitelna, Fio banka, ČSOB Hypoteční banka, Komerční banka, mBank, Modrá pyramida, MONETA Bank, Oberbank, Partners Banka, Raiffeisen stavební spořitelna, Raiffeisenbank, Stavební spořitelna České spořitelny, and UniCredit Bank.