CBA Hypomonitor: Continued Strength This Fall at a Slightly Higher Rate of 5.24%
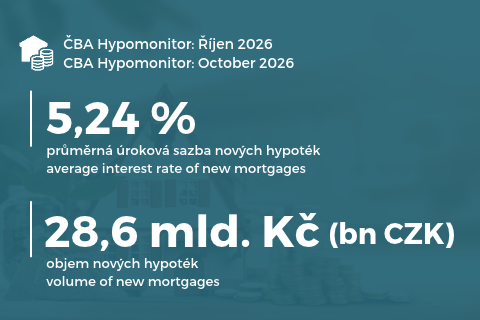
Prague, November 13, 2026 – In October, banks and building societies issued nearly 29 billion CZK in new mortgages (excluding refinancing). Compared to September, the volume remained virtually unchanged. The same applies to seasonally adjusted volumes, which remained slightly below 30 billion in October, with the number of mortgages exceeding 6,300. Since the beginning of the year, the volume of new mortgages has reached 330 billion CZK—approximately 66 billion more than a year ago, representing a one-quarter increase. The average interest rate on new mortgages, in the context of market rate trends, rose only slightly to 5.24% from 5.1% in September, due to the persistently narrow spread relative to market interest rates. This information is based on data from the CBA Hypomonitor, which tracks data from all domestic banks and building societies providing mortgage loans.
The October data also show stabilization at a higher-than-normal level following the August cooling of the mortgage market due to springtime over-stockpiling. Some clients arranged their mortgages earlier in an effort to avoid the impact of higher market rates as well as the CNB’s April tightening of rules for so-called investment mortgages. The seasonally adjusted average number of new mortgages in the fall is close to the long-term average of over 6,400 per month. The average amount of a new mortgage fell slightly to CZK 4.66 million, which we view as a correction following the pre-stockpiling and also as the impact of higher interest rates. However, the mortgage amount remains 8% higher than a year ago, which, at an interest rate of 5.24%, increases the illustrative average monthly payment on a new mortgage to approximately 26,900 CZK, but for half of all new mortgages, the illustrative monthly payment amounts to 21,600 CZK.
These mortgage figures should support the central bank’s wait-and-see approach, even as it adjusts its macroprudential policy for mortgages on November 26. More on this in the CBA Monitor.
Table 1: Summary of Mortgage Volume and Average Interest Rates for October 2026
Monthly figures | Year-to-date figures | ||||||
Volume | Number | Rate | Volume | Number | Rate | ||
Total | 37.2 | 8,353 | 5.22 | 441.6 | 98,670 | 4.71 | |
New loans | 28.6 | 6,154 | 5.24 | 330.0 | 70,200 | 4.73 | |
of which: |
|
|
|
|
|
| |
for purchases | 23.2 | 4,843 | 5.24 | 242.2 | 51,269 | 4.74 | |
for construction | 4.3 | 933 | 5.17 | 53.7 | 11,488 | 4.66 | |
Other | 1.1 | 378 | 5.51 | 34.1 | 7,443 | 4.78 | |
Refinanced from another institution | 7.5 | 1,909 | 5.16 | 95.0 | 24,358 | 4.62 | |
Refinanced internally, increased by | 1.0 | 290 | 5.28 | 16.6 | 4,112 | 4.66 | |
Source: CBA Hypomonitor. Note: Seasonally unadjusted data
Jaromír Šindel, Chief Economist of the Czech Banking Association:“In real terms, the mortgage market remains close to its long-term norm, with over 6,000 new mortgages. This is despite—or rather, due to—the continued modest rise in the actual mortgage interest rate. In October, this rate again only partially eased the pressure from higher market interest rates, reaching 5.24%. However, the real terms of the mortgage rate—which is approaching zero after previously being negative—are also important for activity in the mortgage market.”

Note: The outlook through the end of the year is indicative—it is based on the current trend, not on a model prediction. For the remainder of the year, it assumes a 10% adjustment in the number of mortgages relative to the pace recorded in the second half of 2025. See Chart 7 for an illustration.

October Confirmed That Mortgage Activity Has Stabilized Near Its Long-Term Average
Overall, banks and building societies reported new unconsolidated business in the form of new and refinanced mortgages totaling CZK 37.2 billion in October, which is 4.9% more than a month ago. Year-over-year, the figure fell by 4%. Their total volume so far this year has reached CZK 442 billion, representing a 33% increase compared to January through October of the previous year.
In October, new mortgage loans (excluding refinancing) totaled CZK 28.6 billion. Compared to September, new mortgage activity increased by approximately 2% in volume, which essentially corresponds to seasonal factors. After seasonal adjustment, the October figures for new mortgages showed a slight 0.5% decline to CZK 29.5 billion. The volume of new mortgages thus remains above the average volume of the previous three months (CZK 28.8 billion) and is also approximately 1% higher than in the second half of last year. On a year-over-year basis, the growth in the volume of mortgages granted in October accelerated to 2% following a 5% decline in September. This year, approximately 73% of the volume of new loans was intended for home purchases and 16% for construction.
Marek Richter, Head of Mortgages at Air Bank:“In recent months, the mortgage market has been influenced by rising financing costs, which are also reflected in mortgage offer rates. What’s interesting is the widening gap between the rates currently being offered and the rates at which mortgages are actually being closed. This is because banks typically guarantee the rate for one to two months for applications that have already been accepted. As a result, clients are still securing mortgages at the earlier, lower rates, and the price increases are reflected in the actual agreed-upon rates with a delay.”
The number of new mortgages in October rose by 2.7% month-over-month to 6,154, which is 9% less than a year ago. We estimate that, after seasonal adjustment, the number stands at around 6,343, the same as in the previous three months. Since the beginning of the year, the number of new mortgages has reached 70,200 (+11% year-over-year). Following the CNB’s tightening of conditions and interest rate hike in April, we can expect somewhat lower numbers of new mortgages. Assuming a 10% decline in the number of new mortgages compared to the second half of last year, this year’s new mortgage volume would reach approximately 82,000, which would be nearly 8% higher than last year. However, this would still remain below the average of around 95,000 from 2016 to 2018 and below the record high of 114,000 set in 2021.
Chart 2: Newly Granted Mortgages (Excluding Refinancing
) Stabilization in October near the levels seen in September of this year or around the second half of last year …

Source: Czech Banking Association, CNB, CZSO, Flat Zone.
Chart 3: Average Mortgage Amount by Purpose
… and the average amount of a new mortgage also decreased slightly to 4.66 million CZK.

Source: CNB, CBA Hypomonitor
The volume of refinanced and increased loans (whether internally or from another institution) rose to 8.5 billion CZK in October. This is 20% more than the average of 7.1 billion refinanced last year. The share of refinanced loans in the total volume of mortgages granted then rose to nearly 23%, exceeding last year’s 21% average. This exceeds the 17.2% share seen in 2022–2023, though it remains below the nearly 29% share from 2020–2021, when households refinanced at a mortgage rate of 2.14%. In October 2026, households refinanced at an interest rate of 5.17%, which is, however, 0.7 percentage points higher than the 4.46% rate a year ago. Higher refinancing volumes this year reflect the convergence of expiring longer-term fixed-rate periods from the era of low interest rates and shorter-term fixed-rate periods from the recent period of higher interest rates.
Despite the increase, the share of external refinancing in expiring fixed-rate periods remained below 26% —the same share as in the first half of this year—which may also indicate a certain degree of pre-stockpiling of lower interest rates even for this year’s expiring fixed-rate periods. The increased volume of refinancing reflects a combination of longer-term fixed-rate periods from the era of exceptionally low rates and shorter-term fixed-rate periods from the recent period of higher interest rates. For some households, this refinancing means a noticeable increase in monthly payments; conversely, for loans taken out in 2023 with a mortgage interest rate of 5.82%, it may bring some relief.
The average effective mortgage rate rose to 5.24% and once again only partially alleviated the pressure from higher market interest rates
The average effective interest rate on new mortgages rose further in October to 5.24% from 5.1% in September. The October rate is thus just under 0.8 percentage points higher than the 4.48% rate a year ago, which increases the illustrative average monthly payment on a new mortgage by 2,000 CZK—approximately 2% of the applicant’s net income. By comparison, the average mortgage rate in 2025 reached 4.58%, compared to 5.07% in 2024.
At 5.24%, the October mortgage interest rate was just under 0.4 percentage points above the October average of relevant market swap rates. The spread has thus remained significantly narrower in recent months compared with the long-term average of around one percentage point. Banks have only gradually passed on the recent rise in the market cost of funds to customer rates. The November decline in market interest rate swaps (see Chart 5), despite the CNB’s interest rate hike to 4%, provides some relief from the pressure on mortgage rates. The decline in swap rates reflects a possible easing of tensions surrounding Iran and, more generally, the outcome of the U.S. November elections. However, inflation in both the Czech Republic and the U.S. serves as a reminder that central banks are far from adopting a dovish stance that would reverse the previous rise in market interest rates.
In our study, we highlighted structural factors—primarily the strength of demand in a competitive market—that influence the pass-through of market rates to mortgage rates. For more details, see here: Mortgage standards have tightened, but strong demand has mitigated the impact on lending conditions.
Czech longer-term market interest rates [1] for the three-year interest rate swap rose slightly in October by just under one-tenth of a percentage point to 4.86%, placing them 1.4 percentage points above the February level (mortgage rates in October were 0.8 percentage points above the previous low set in March of this year). U.S. five-year interest rate swaps rose to 4.91% in October and were 1.05 percentage points above their 2025 average. Euro-denominated five-year swaps remained essentially unchanged at 3.46% in October and were 1.12 percentage points above their average level of 2.34% last year.
[1]These are primarily long-term interest rate swaps (IRS), which reflect the cost of money over longer maturities—in recent years, around 3 to 5 years, but more recently around 3 years. Alternatively, shorter-term fixed rates are used, while 10-year maturities are less relevant due to higher central bank rates compared to the previous decade, as well as due to the costs incurred when paying off mortgages early.
Chart 4: Average Mortgage Interest Rate – New Loans
The October mortgage rate once again reacted more gradually to the previous rise in the market price of money

Source: CNB, CBA Hypomonitor
Chart 5: Renewed U.S. attacks on Iran are keeping market swap rates higher
… which reached their highest levels since May 2023 in October, followed by a relief rally in early November

Source: Macrobond (November 11, 2026), CBA
The average monthly payment rose to approximately 26,900 CZK, with a median of 21,600 CZK
Rising interest rates and higher average mortgage amounts in October 2026, compared with the average values from 2025, increased the average monthly payment on newly issued mortgages by 4,200 CZK. Table 2 illustrates scenarios for the development of monthly payments for various mortgage terms. The table suggests that the increase in mortgage rates by nearly 0.7 percentage points from their 2025 average of 4.58 percent resulted, for an average mortgage size with a typical repayment term of approximately 27 years, an increase in the monthly payment of just under 1,800 CZK to approximately 26,900 CZK—that is, 1.7% of the applicant’s net income compared to last year’s average payment. Compared to the average mortgage rate of 5.07% in 2024, the change due to the interest rate amounted to just under 500 CZK for a mortgage at its current average value.
However, the current average mortgage amount was 11% higher than its average amount in 2025, which contributes to an increase in the monthly payment of 2,600 CZK compared to last year’s average monthly payment—based on last year’s average mortgage amount but at the current interest rate. The monthly payment on a one-million-koruna mortgage with a 30-year term is around 5,500 CZK at current interest rates.
The impact of interest rates on expiring fixed-rate periods varies in terms of mortgage trends, depending on the year in which the interest rate was fixed. Illustrative examples? Compared to the average 2.33% mortgage interest rate for new mortgages in 2021, the current refinancing rate of 5.17% —when the loan term is shortened—increases the monthly payment on an average mortgage by nearly 4,100 CZK, or about 7.8% of the current gross average wage. However, that wage has increased by 35% compared to the end of 2021. Conversely, the current interest rate would reduce the monthly payment on a 2023 mortgage with an interest rate of 5.82% by about 1,100 korunas. In 2027, mortgage refinancing from 2024 with an interest rate of 5.11% will dominate, with the current interest rate level representing an increase of approximately 192 koruna. We discussed the impacts and circumstances in Fokus CBA: The wave of mortgage refinancing is gaining momentum, but the interest rate shock is subsiding. Higher inflation remains a risk.
Table 2: Illustration of Monthly Payments for an Average and Median Mortgage Based on Loan Term and Interest Rate

Source: CBA (the table with values is available in an XLS file attached to this report). Note: The colored column corresponds to the interest rate from the latest CBA Hypomonitor report combined with the typical repayment term; other rates are for illustrative purposes only. The colored row corresponds to the average and median maturities of new mortgages according to CNB data; amounts are rounded to the nearest ten crowns. The median monthly payment is based on the median mortgage amount. This is calculated based on the ratio of the average to the median amount of new mortgage loans over the last three quarters, according to CNB statistics (118.7%). The calculation also assumes an average maturity of 30 years (corresponding to the median) and an average interest rate, since the difference between the average and median rates has been negligible over the long term (approximately 0.045 percentage points). Unlike the average, the median represents a typical value—half of the loans are lower and half are higher—and is not influenced by extreme values.
The average amount of new mortgages fell slightly in October to 4.66 million CZK
Although the average size of newly granted mortgages fell slightly month-over-month in October, it remains 8% higher than the CZK 4.33 million recorded a year ago. The higher average mortgage amount at the beginning of this year—when it reached CZK 4.85 million between March and May—likely reflected the lingering effect of pre-stockpiling in so-called investment mortgages. For these, the CNB tightened requirements starting in April, specifically setting the LTV at 70% and the DTI at seven times annual income. Based on CNB data from the Financial Stability Report, we estimate that the average amount of an investment mortgage— i.e., mortgages for additional owner-occupied housing or rental properties, was roughly 29% higher last year and in the first quarter of this year than for owner-occupied mortgages and other truly new mortgages.
The average mortgage amount is also closely linked to trends in real estate prices. In the second quarter, year-over-year growth in these prices slowed only slightly to 8.6%. In the second quarter, the growth in asking prices for apartments slowed to 1.4% quarter-over-quarter from 2.7% in the first quarter, falling below their long-term average increase of 1.8%. However, the growth in actual sale prices remained at 2.5% quarter-over-quarter, signaling a possible future slowdown to 10% year-over-year from 12.3% in the second quarter. According to data from Flat Zone, the transaction price of apartments sold in the second quarter rose to nearly 100,000 crowns per square meter, exceeding 165,000 in Prague. This is 8.3% and 9.7% higher, respectively, than a year ago (see charts on CBA Monitor). However, a more significant slowdown in price growth will continue to be held back by a combination of supply-side constraints and stronger mortgage pre-stockpiling, as well as still-solid real household wages (4.3% year-over-year in Q2-2026; see chart here) and disposable income.
Chart 6: Illustrative comparison of monthly payments for the current average newly issued mortgage versus the same period a year ago, based on the interest rate, mortgage amount, and loan term in years
Year-over-year, the rise in mortgage rates led to an increase in the average monthly payment of 2,070 CZK, while the rise in the average mortgage amount caused an increase of 1,880 CZK. However, the average mortgage amount has stabilized in the last two months at approximately 200,000 korunas below the spring level, which offset the impact of the higher interest rate.

Source: CBA. Note: Amounts are rounded to the nearest ten crowns.
Statistical Appendix
Chart 7: Seasonality of New Mortgage Loans

Source: CBA Hypomonitor
Note: These are truly new mortgages (i.e., excluding refinancing and loan increases). The underlying data are available in an XLS file attached to the CBA Hypomonitor website. The outlook through the end of the year (fcst) is based on current conditions—it reflects the current trend rather than a model-based forecast. However, for the remainder of the year, it assumes a 7% adjustment in the number of mortgages relative to H2-2025.
Chart 8: Breakdown of New Mortgage Loans by Purpose

Source: CBA Hypomonitor
Note: The latest figure represents the average for the past 12 months. The interpretation of the other segment may be skewed by the inclusion of so-called mortgages without real estate arranged without a specific purpose. For more details, see the methodological note below.
In 2025, the mortgage market saw strong growth in volume—up 41%—and an increase of nearly a quarter in the number of loans
Throughout 2025, banks and building societies provided new mortgage loans totaling 321 billion CZK. That is 93 billion CZK more than the 228 billion CZK recorded in 2024. This year-over-year jump represents a 41% increase. In addition, mortgages totaling 85 billion CZK were refinanced, bringing the total mortgage market to 406 billion CZK in 2025, up from 275 billion in 2024. If we adjust the volumes for the rise in apartment prices of around 15–16% (according to various statistics), the volume of new mortgages increased by slightly less in real terms. This also corresponds to a more moderate increase in the number of new mortgages in 2025—by just under a quarter to more than 76,110—and a nearly 15% increase in the average amount of new mortgages granted to 4.21 million CZK.
New mortgages in 2025 were financed at an average interest rate of 4.58%, which was half a percentage point lower than in 2024, while the spread relative to the market swap yield curve reached just under one percentage point, slightly below the long-term average. The average monthly mortgage payment in 2025 was just under 22,800 CZK, which is 8.6% more than in 2024, and slightly exceeded last year’s increase in the average nominal wage, which was likely more than 7%. The average year-over-year increase in the monthly mortgage payment of approximately 1,800 korunas in 2025 primarily reflected a higher average mortgage amount, with an increase in the payment of nearly 2,900 korunas, while the lower mortgage interest rate reduced the average monthly payment by more than 1,200 CZK.
Chart 9: Annual Volume, Number, and Average Amount of Mortgages Granted from 2020 to 2025

Source: CBA Hypomonitor
The Czech Banking Association Publishes Aggregate Statistics for the Entire Banking Market
The Czech Banking Association, in cooperation with its member banks, publishes new summary statistics on the housing market. These primarily include the volumes and numbers of newly issued and refinanced mortgages, as well as the corresponding interest rates. The CBA publishes these statistics in aggregated form for the entire banking sector on a regular basis, typically around the middle of each month. All domestic banks and building societies providing mortgages in the Czech Republic participate in the survey. The data is available starting in January 2020 in the attached file at www.cbaonline.cz, where the relevant statistics can also be found separately for banks and building societies. The figures listed above represent the sector as a whole and can also be viewed in a simple graphical format on the website cbamonitor.cz.
CBA Hypomonitor Methodology
The CBA Hypomonitor categorizes mortgage loans provided by banks and building societies to households into several categories to distinguish new loans from refinanced loans or internal rate adjustments. New loans are then reported in categories based on the purpose of the loan:
1. New Loans
These are loans whose entire amount enters the economy for the first time. Loan consolidation or refinancing does not fall into this category. They are divided into three categories:
· Purchase of real estate
· Real estate construction—including real estate renovation
· Other new agreements—only new loans that are in no way related to the purchase or construction of real estate (which does not apply in the case of so-called mortgages without real estate arranged without a specific purpose), i.e., for example, so-called American mortgages, settlement of joint marital property, reimbursement of the purchase price, settlement of an inheritance share, settlement of a cooperative share, etc.
2. Refinanced loans from another financial institution
These are loans created by refinancing one or more loans from a financial institution other than the reporting one. Regardless of the amount refinanced and regardless of the amount of any increase, the total amount of the newly created loan is reported in this category.
3. Increased or internally refinanced loans
These are loans that were already part of the reporting entity’s portfolio in the previous reporting period and for which one of the following changes occurred during the reporting period:
· an increase in the agreed amount
· changes occurred such that the original loan was refinanced or converted into a new loan within the reporting entity. This constitutes a truly new contract, not, for example, merely a new arrangement as part of the refixing of an existing contract. Therefore, the volume of such loans in the CBA statistics is lower than that of “other new arrangements” in the Czech National Bank’s statistics.
Data for the CBA Hypomonitor are provided by the following banks and building societies: Air Bank, Česká spořitelna, ČSOB, ČSOB Stavební spořitelna, Fio banka, ČSOB Hypoteční banka, Komerční banka, mBank, Modrá pyramida, MONETA Bank, Oberbank, Partners Banka, Raiffeisen stavební spořitelna, Raiffeisenbank, Stavební spořitelna České spořitelny, and UniCredit Bank.