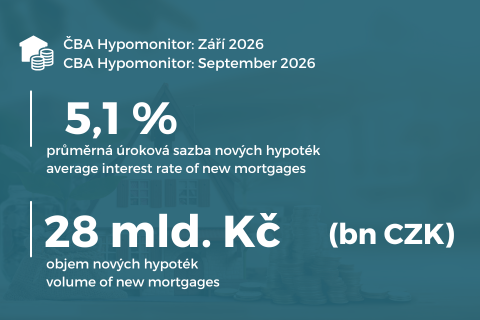
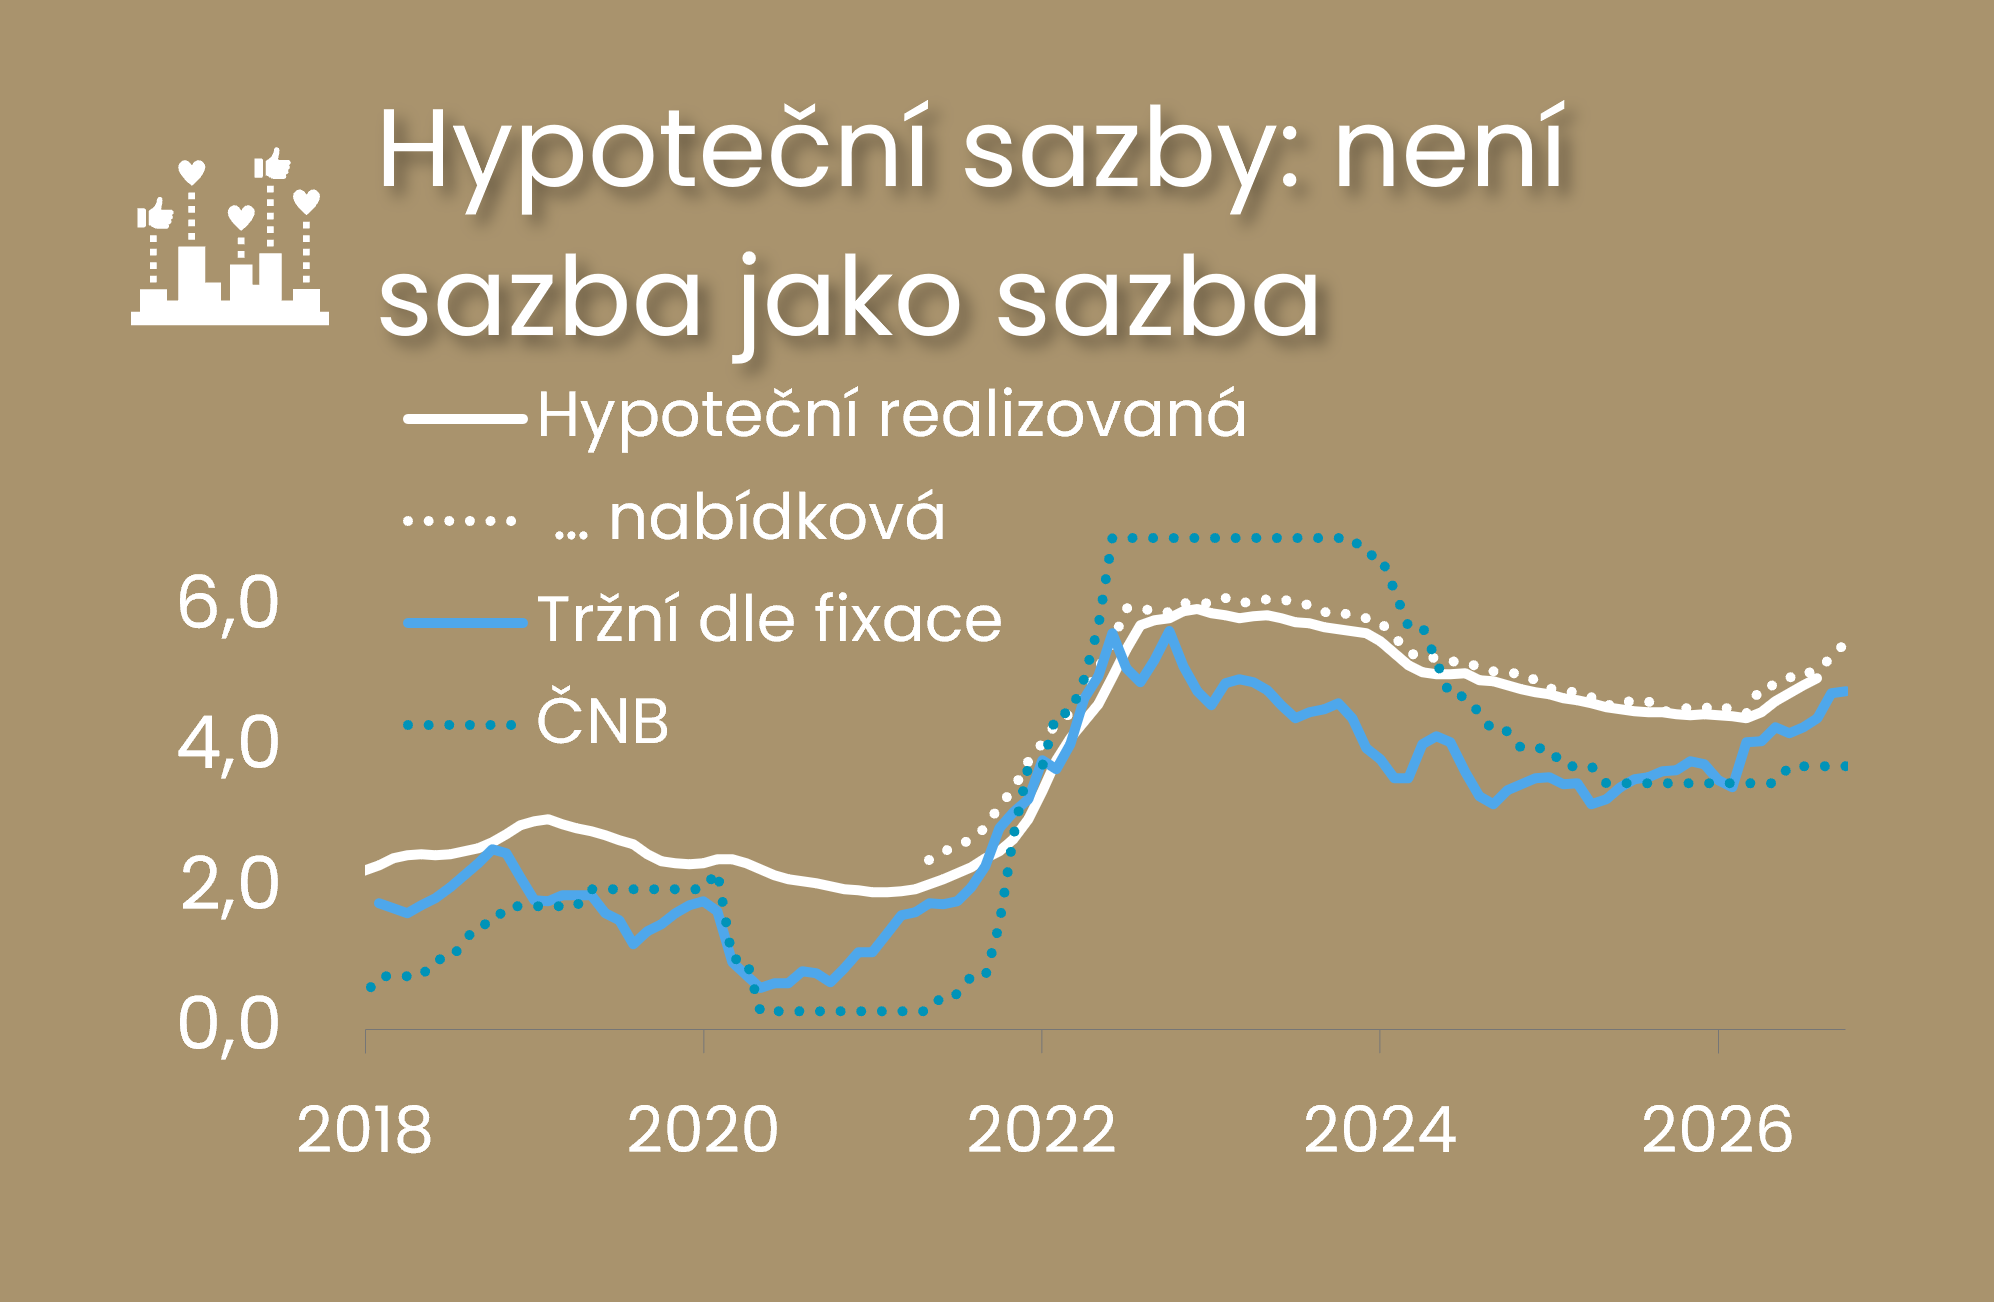
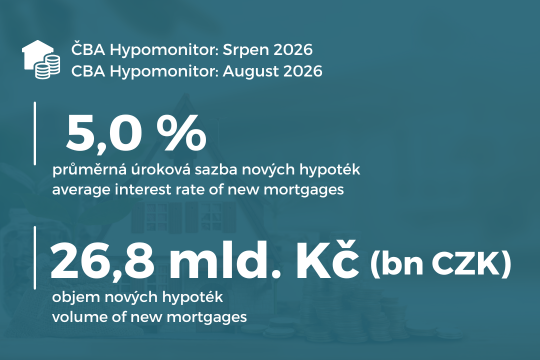
The average interest rate on new mortgages rose slightly in September to 5.1% from 5% in August. The September rate is thus 0.58 percentage points higher than the 4.52% rate a year ago, which increases the illustrative average monthly payment on a new mortgage by 1,500 CZK, or approximately 1.5% of the applicant’s net income. For comparison, the average mortgage rate in 2025 reached 4.58%, compared to 5.07% in 2024. Hypomonitor’s history since 2020 shows its lowest recorded value at 1.95% in January 2021 and its highest level at 5.98% in December 2022. At 5.1%, the September mortgage interest rate was 0.31 percentage points above the average market interest rate swap rates—that is, the cost of money— whereas in the previous three months this spread stood at 0.57 percentage points. The August spread is approximately 0.72 percentage points below the long-term average since 2014, which stands at 1.03 percentage points.
Average Interest Rate on New Mortgages
CBA Monitor
You can hide a data set by clicking on the data set name in the chart legend.
Source of primary data
ČBA Hypomonitor, CNB
Category
ČBA Hypomonitor
Data Frequency
monthly
Note
In the case of ČBA rates, these are agreed-upon interest rates p.a. In the case of ČNB rates, these are agreed-upon rates converted to an annual basis (the so-called annualized AAR rate). A more detailed breakdown of the data from the ČBA Hypomonitor is available in its monthly data appendix; see: https://www.cbamonitor.cz/publicistika/soubory/cba-hypomonitor-data
Compared to August, their volume increased by 5%, even though in recent years it has typically declined month-over-month in September
Jaromír Šindel
08. 10. 2026
The market price of three-year funds has risen by approximately 1.4 percentage points since February, while mortgage rates have risen by roughly one point. The rise in market rates has thus been only partially reflected in mortgage rates so far. It is important to distinguish between the aggregate offered rate, the rate for the most commonly chosen fixed-rate term, and the interest rate that the client actually negotiates. The spread between mortgage and market rates—which should not be confused with net profit—has long been among the lowest in the EU for banks in the Czech Republic and has even fallen below its long-term average in recent years. This is also consistent with banks’ lower net interest margin, expressed as the ratio of net interest income to assets.
Jaromír Šindel
17. 09. 2026
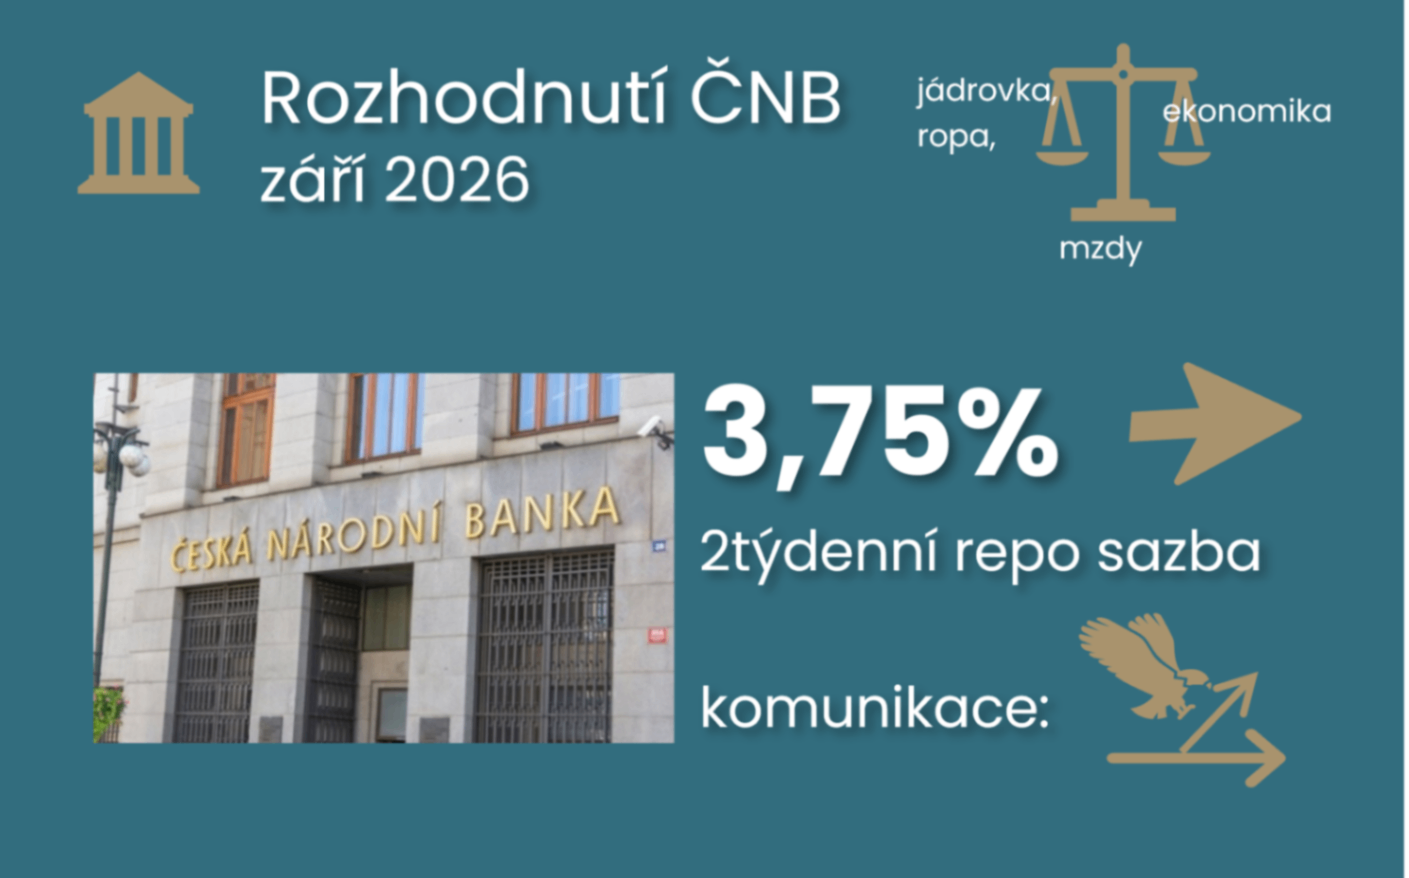
The September decision was unanimous, and the Bank Board did not consider it necessary, for the time being, to follow up on the June rate hike with a further tightening of monetary conditions. Furthermore, financial conditions are tightening due to rising longer-term market rates, which are also affecting lending. In November, the CNB will revisit the question of whether to keep the rate at 3.75% or raise it to 4%. The second option seems more likely to me, unless there is a significant cooling off in domestic data or a normalization of commodity prices. Meanwhile, the market expects an even more pronounced rate hike to 4.75% over a nine-month horizon. However, the Czech yield curve is also significantly influenced by foreign rates, partly due to domestic factors. The CNB’s leeway to not place greater weight on these developments will depend primarily on the future trajectory of core inflation and the koruna exchange rate, the importance of which was also emphasized by the governor.
Jaromír Šindel
16. 09. 2026
Activity declined by 13 percent in terms of volume compared to July
Jaromír Šindel
14. 08. 2026
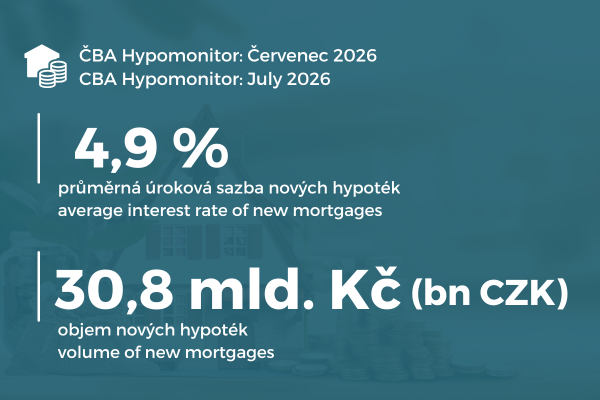
The average mortgage rate rose to 4.9%. The July mortgage figures reveal four main trends. First, both the number and volume of new mortgages have stabilized at lower, but still strong, levels. Second, the rise in actual mortgage rates remains gradual compared to market rates. Third, rates on refinanced mortgages no longer deviated downward as significantly as they did in May and June. And fourth, the likely lower share of investment mortgages contributed to a further decline in the average amount of new mortgages.
Jaromír Šindel
17. 07. 2026
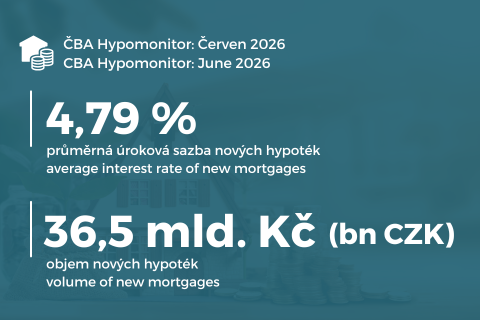
The average interest rate on new mortgages rose to 4.79%, while the average mortgage amount fell back below 4.7 million crowns. Banks and building societies issued new mortgages (excluding refinancing) totaling 36.5 billion crowns. After months of exceptionally strong mortgage activity, June saw a clear return to the robust normal levels seen in the second half of last year. In the first half of the year, the volume of new mortgages reached 216 billion crowns, which is 66 billion more than last year. Higher market interest rates and expensive real estate remain the main obstacles.
Jaromír Šindel
12. 06. 2026
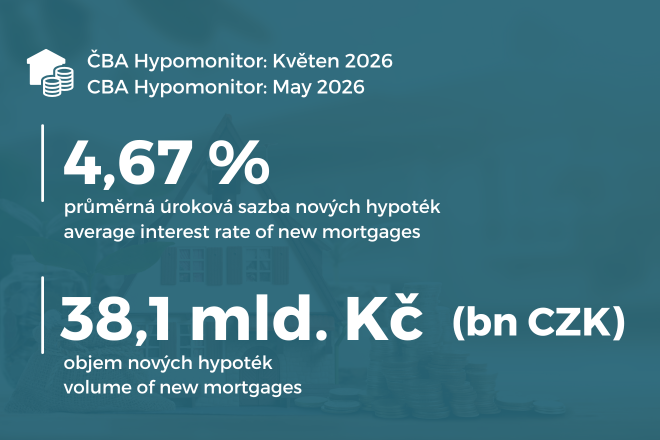
In May 2026, banks and building societies actually issued new mortgages (excluding refinancing) totaling CZK 38.1 billion.
Jaromír Šindel
18. 05. 2026
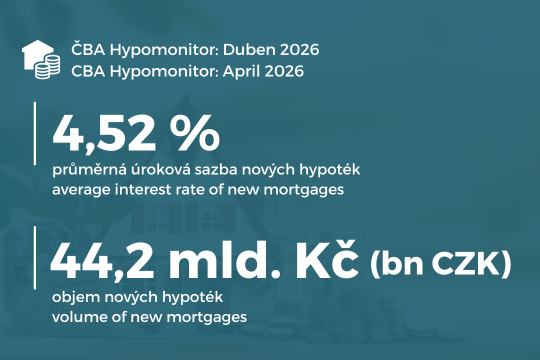
Average mortgage rate rises to 4.52%
Jaromír Šindel
13. 05. 2026
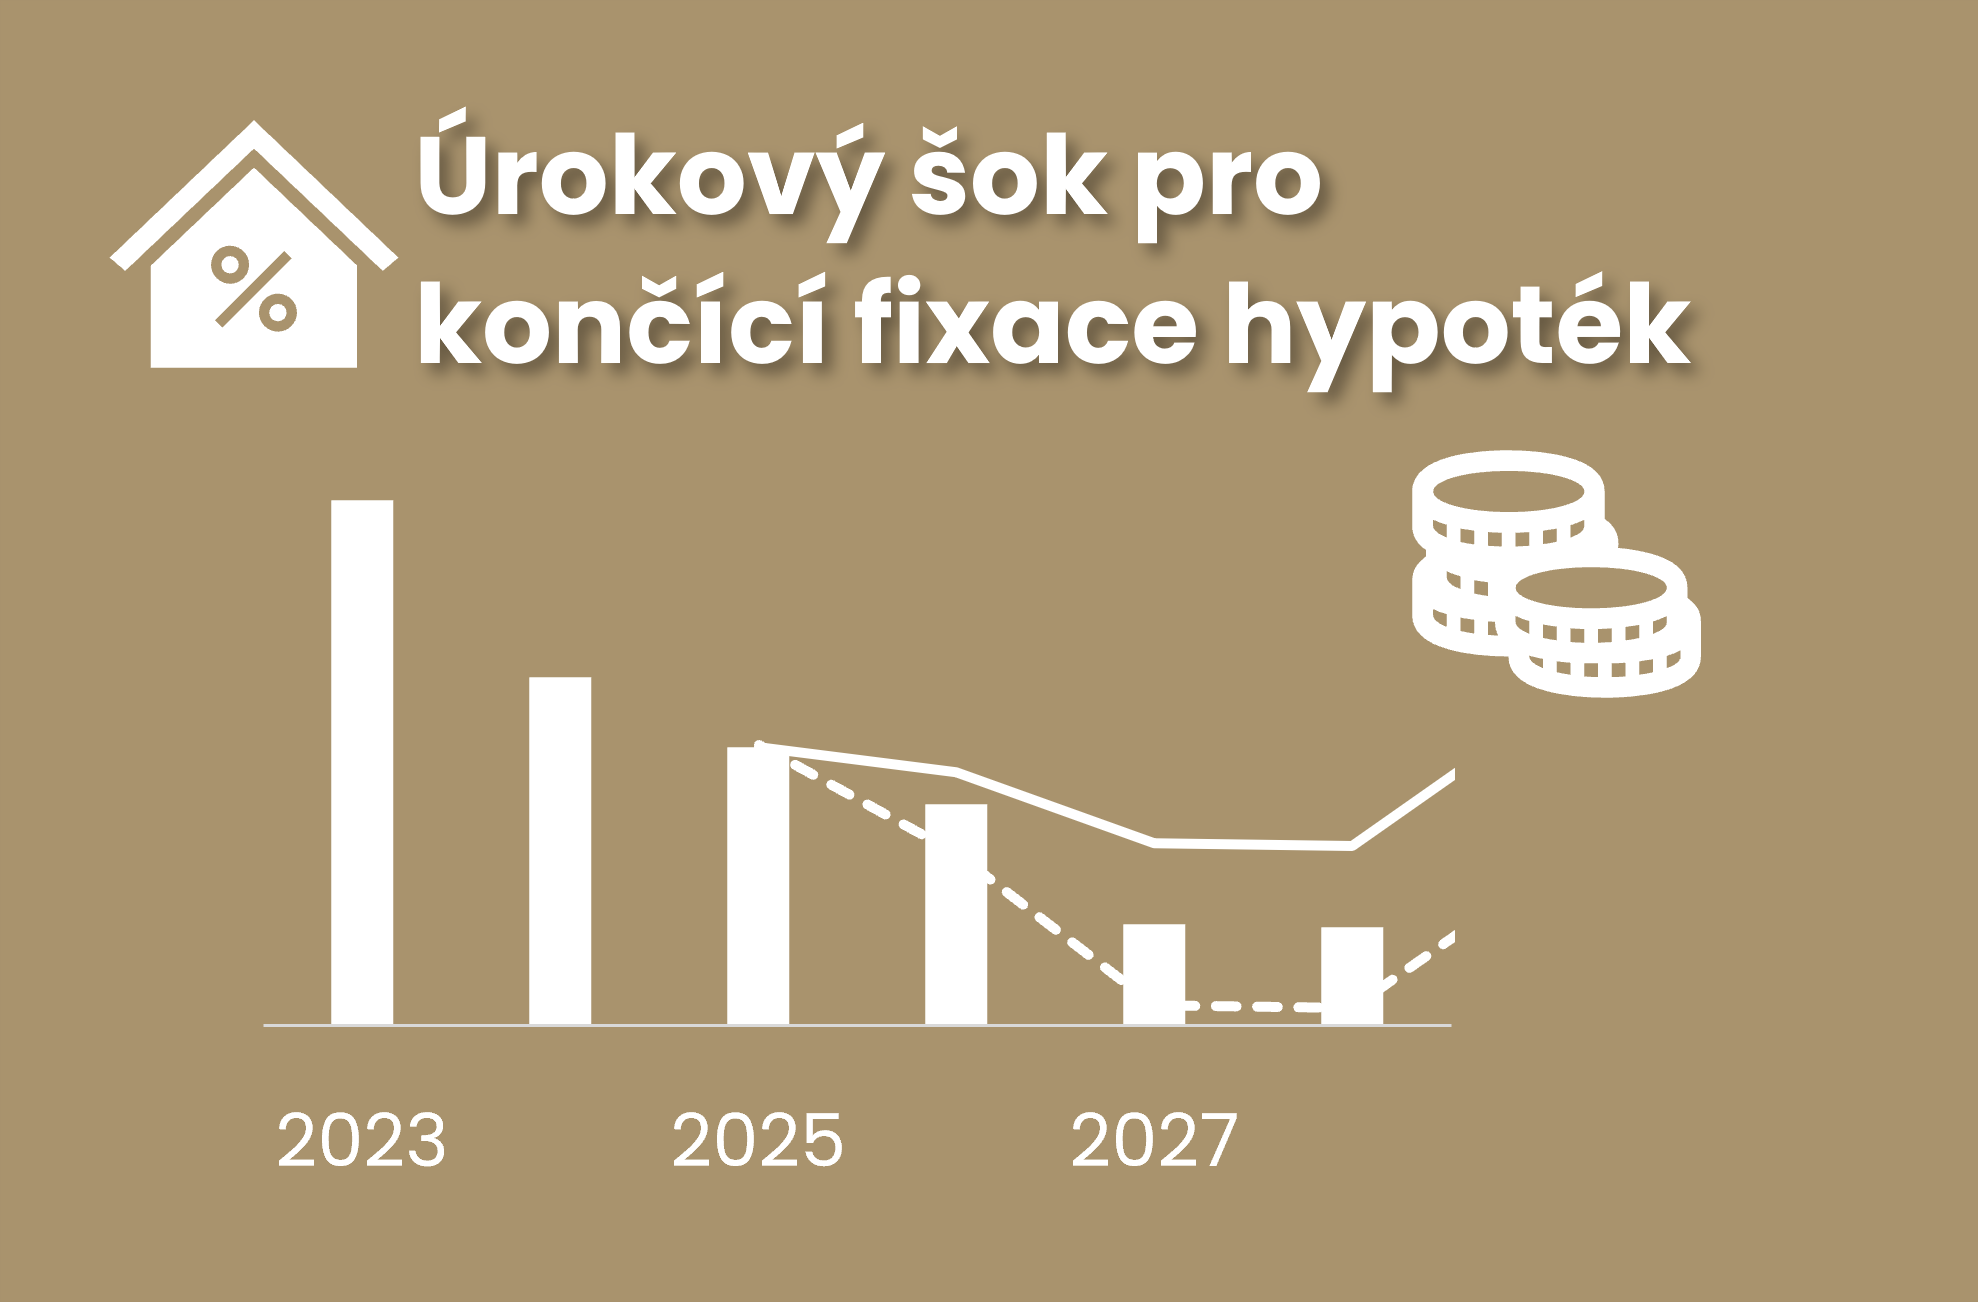
This year is bringing a strong wave of expiring mortgage rate fixations, while the shorter fixation periods agreed in recent years will further increase these volumes in the years ahead. Building on the central bank’s latest estimate that mortgage fixations worth an average of CZK 534 billion per year will expire between 2026 and 2028, we present alternative interest-rate shock scenarios depending on the path of mortgage rates. In 2027–2028, the negative interest-rate shock is expected to ease to 0.1–0.6 percentage points, down from 1.1–1.4 percentage points this year. However, we also outline a more adverse scenario involving a stronger interest-rate shock. This year, the negative interest-rate shock affecting expiring mortgage fixations from the low-rate period will amount to roughly 3.5% of the average household income of mortgage applicants, although across all households the average impact will be about half that level. In both cases, the expected real growth in wages and salaries should be sufficient to offset the shock.
Jaromír Šindel
16. 04. 2026
The average amount of a new mortgage exceeded CZK 4.8 million
Jaromír Šindel
15. 04. 2026
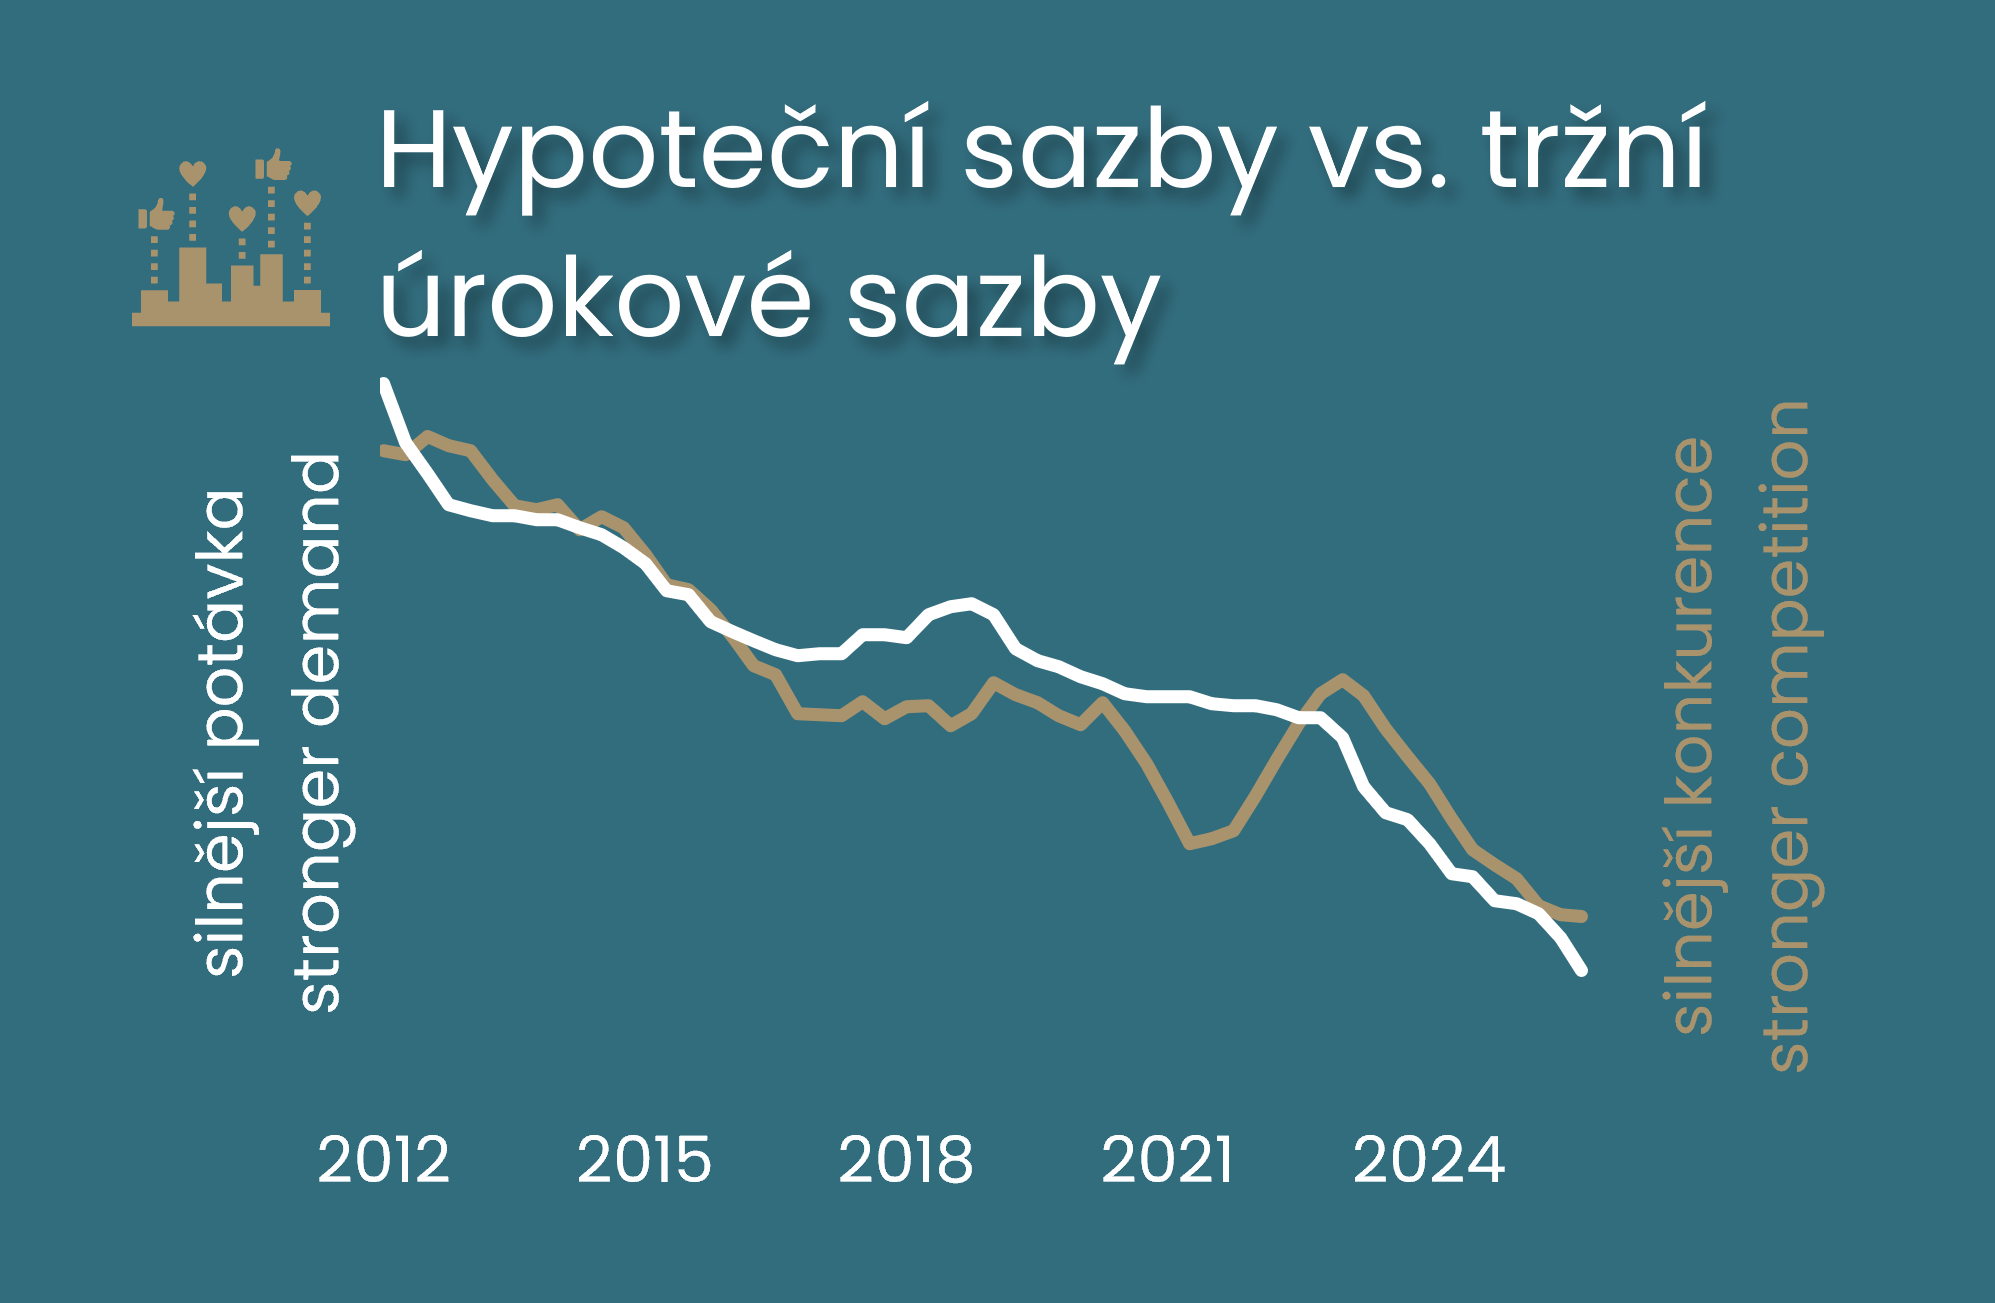
Comment by Jaromír Šindel, Chief Economist of the CBA: Mortgage rates are significantly determined by the movement of market interest rates. However, structural factors in the banking market are also important. The CNB's investigation of credit conditions in our analysis helps to explain what factors influence the difference between mortgage and market interest rates deviating from its normal level. The CBA analysis shows that a combination of stronger demand and competition among banks plays a key role. It is the latter that can lead to more favourable rates for clients without undermining market stability. The difference between mortgage rates and market rates that we have been monitoring is therefore mainly dampened by stronger demand, but in an environment of growing competition, which is key. Banks' profitability also plays a role, acting as a corrective mechanism to maintain competitive interest rate spreads but also market stability.
Jaromír Šindel
13. 03. 2026
February ranked among the five strongest mortgage months ever in terms of volume in billions of crowns, but also with a continued strong number of new mortgage originations.
18. 12. 2025
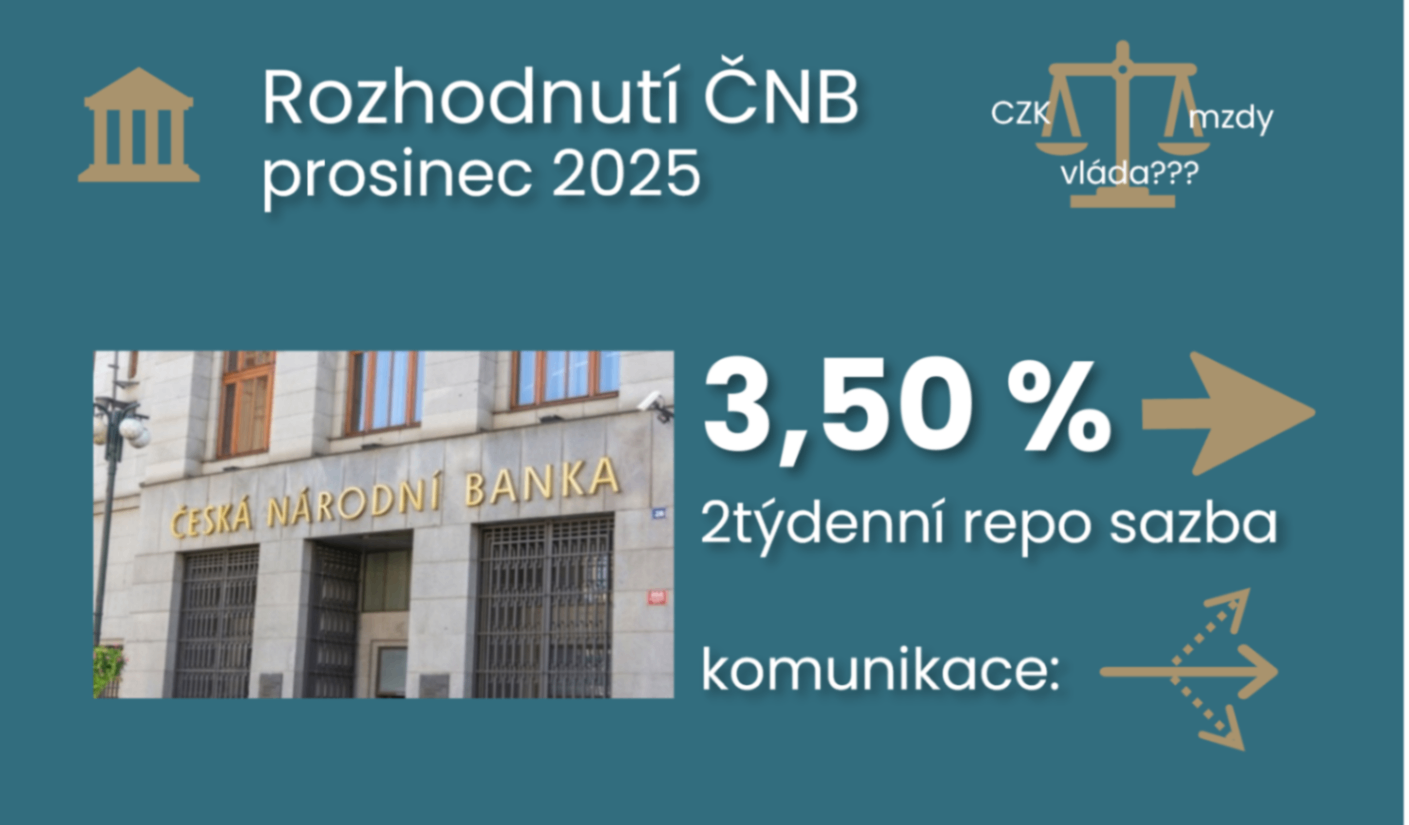
Comment by Jaromír Šindel, Chief Economist of the CBA: The central bank did not surprise by unanimously leaving interest rates unchanged, i.e. with the two-week repo rate at 3.50%, for the fifth meeting in a row after a 25bp cut in May. Although the Board did not change its view of the risks and uncertainties surrounding the CNB's November forecast, it did assess the risks to inflation as balanced, given the risks in financial markets and the removal of the renewable energy levy, following November's upside assessment.
15. 07. 2025
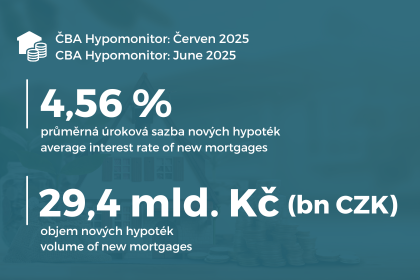
In June 2025, banks and building societies granted new mortgages worth CZK 29.4 billion.
16. 05. 2025
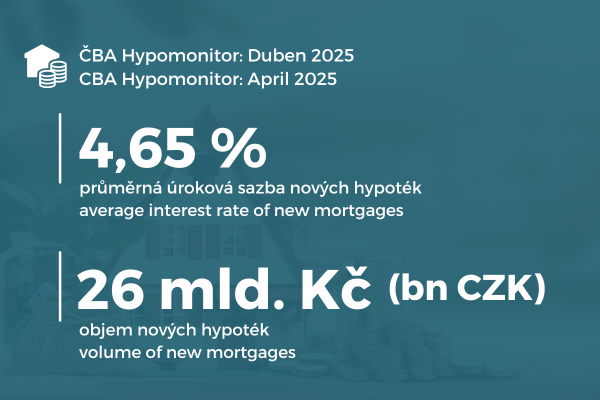
Despite the slight correction, April continued to see strong volumes of new mortgages supported by another slight decline in the average mortgage rate to 4.65%.
14. 04. 2025
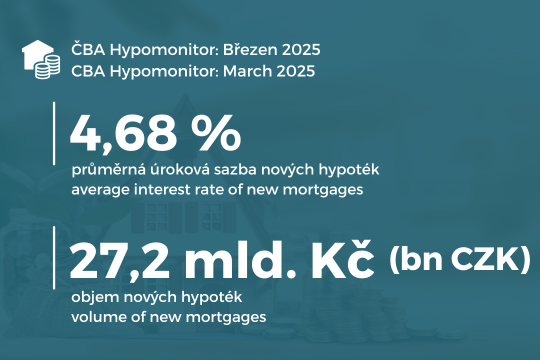
March continued to see strong new mortgage volumes supported by another slight fall in the average rate to 4.68%