Higher core inflation is pushing the CNB to raise interest rates to 4% in November
Regarding the central bank's decision:
The central bank’s November meeting will likely result in a quarter-percentage-point increase in its two-week interest rate to 4%.
The September acceleration of consumer inflation to 2.5% year-over-year brought an unwelcome surprise in the form of a return to higher core inflation growth above 3%.
From the perspective of its inflation target, the central bank is grappling not only with the geopolitical impacts of higher energy prices but also with the persistent inflationary pressures within the Czech economy. This is reflected in the continued lag of wage growth behind productivity, and a looser fiscal policy without structural changes does not make the central bank’s job any easier. The stronger momentum of core inflation, coupled with the economy’s still solid—albeit weaker—performance, poses a risk that the secondary effects of higher energy prices will spill over.
In this situation, the central bank can likely no longer rely solely on tighter financial conditions—which have dampened the mortgage market through higher long-term market rates—and will have to step in by raising short-term interest rates. The CNB’s hawkish stance may dampen the impact on longer-term market interest rates, as the market has already priced in monetary policy tightening (see chart below).
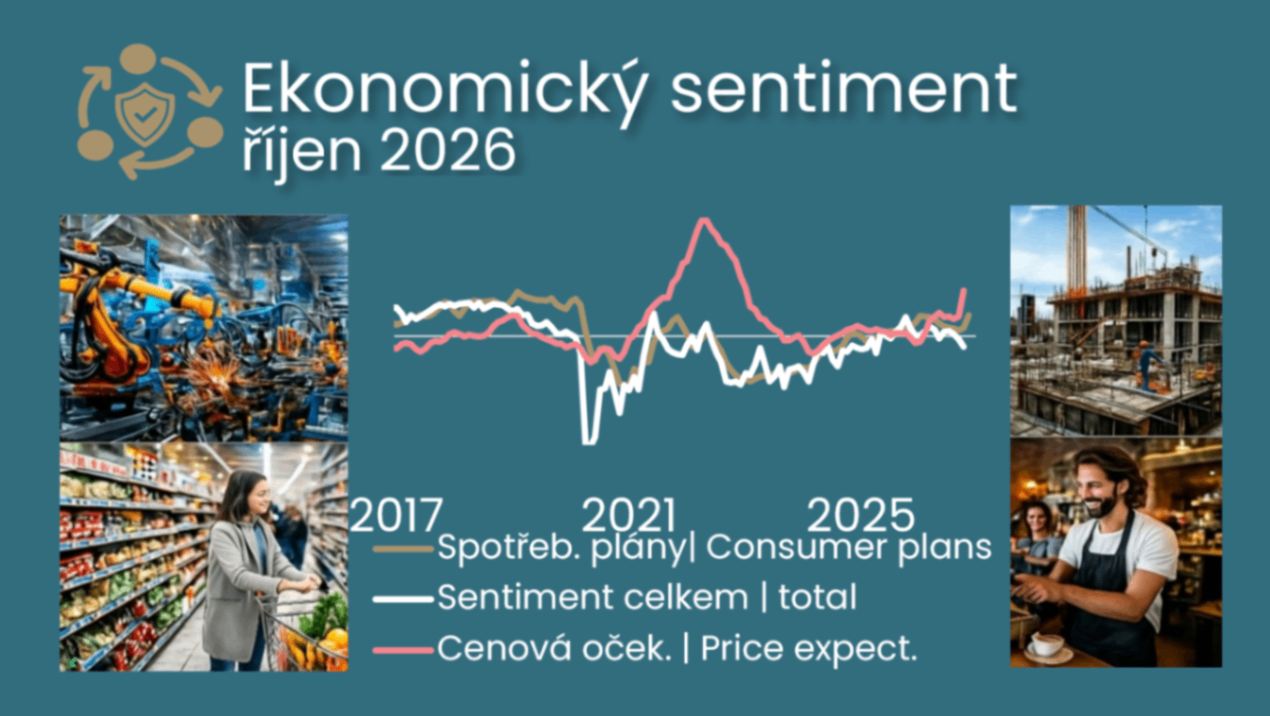
The decline in October sentiment should not significantly affect the central bank’s hawkish communication, although the drop in more volatile industrial production expectations poses a risk (see charts below). However, price expectations in both the industrial and services sectors have risen significantly, and households’ plans for increased future spending maintain the hawkish tone of October’s sentiment.
Nevertheless, the persistent oil shock poses not only a risk of higher prices but also a downside risk to economic growth. To some extent, this will be part of the central bank’s communication, which will thus fall short of market expectations—the market anticipates that the CNB will raise its interest rate to 4.75% next summer.
Regarding the central bank’s new forecast:
Both August and September core inflation, with an average growth rate of just over 3 percent, rose by two-tenths of a percent faster than the central bank’s forecast had anticipated. This, combined with higher oil prices, will put pressure on the CNB’s inflation outlook for the coming years, which in August projected a 2.5% increase.
On the other hand, higher oil prices and a slower recovery of the Czech economy in the first half of the year are likely to lower the CNB’s economic growth outlook, which had projected a 2.7% acceleration in GDP growth for 2027.
The CNB will likely also adjust its outlook for the 3M PRIBOR, which will start at 4 next year but will still be closer to 4% than current market expectations, which anticipate 4.75% by next summer.
The Czech Banking Association’s (CBA) August forecast, projecting 2.3% GDP growth and 2.6% consumer inflation in 2027, also faces the risk of stagflation. According to a May sensitivity analysis, a return of oil prices to $100 per barrel could reduce the growth of the Czech economy over a two-year horizon and increase inflation by more than half a percentage point. In such a scenario, the monetary policy response could result in a CNB rate of around 4%, or possibly as high as 4.25%, if we take into account the risk of a higher interest rate in the baseline scenario.
Two sets of economic data that are likely to have the greatest impact on the CNB’s November interest rate discussion:
1) The core inflation rate has risen back above three percent

2) The price of oil is significantly higher than the CNB’s August forecast

Markets are pricing in a more significant increase in the CNB's interest rate ...

... but also in the case of the ECB and the Fed ...

... which, if the CNB keeps its rates unchanged, could result in a weaker koruna ...
..., which has already happened to some extent following the CNB's stabilization in September due to a less supportive interest rate differential, ...

... although the weakening of the euro against the U.S. dollar—that is, the decline in the EUR/USD exchange rate—also played a role.

Economic sentiment in October deteriorated, primarily due to a decline in more volatile expectations in the industrial sector. However, price data, combined with persistently high core inflation, send a negative signal to the CNB in terms of its inflation target.
Economic sentiment worsened in October, primarily due to the manufacturing sector

Despite the decline in economic sentiment below the long-term average, households' purchasing plans—this time for the future—remained high

¨Price expectations have risen significantly in both the manufacturing and service sectors

In the services sector, rising price expectations pose a risk given the segment’s continued strong momentum in core inflation

Industrial capacity utilization has returned to slightly below the long-term average

The labor shortage remains, once again, a major obstacle primarily in the construction sector, while the manufacturing sector continues to grapple with weaker demand
