Unemployment

5.10 % (08-2026)
Unemployment Rate (registered unemployed, SA)
3.11 % (08-2026)
General Unemployment Rate (Trend Cycle)

Commentary by the Czech Bar Association

We estimate that in October 2026, the seasonally adjusted registered unemployment rate rose to 5.1% from 5.02% a month earlier. According to data from the Labor Office, the unadjusted unemployment rate reached 5% in October, up 0 percentage points from the previous month. The month-over-month change in the unadjusted unemployment rate in October thus primarily reflects a cyclical increase in unemployment, which was partially offset by a seasonal improvement.
In a year-over-year comparison, the October unemployment rate is 0.4 percentage points above the 4.6% level recorded in October 2025.
In 2025, the unemployment rate stood at 4.4%, and this year’s average so far is 5%. Compared to the start of Russia’s invasion of Ukraine, the unemployment rate is thus 1.8 percentage points above the 3.3% level from the first quarter of 2022 and is 2.3 percentage points higher than the pre-COVID average of 2.8% in 2019. Since 2005, the registered unemployment rate, according to our seasonally adjusted estimate, reached its lowest level of 2.7% in January 2020, while its highest level of 8% was recorded in January 2014.
The different concept of the sample unemployment rate, as measured by the Czech Statistical Office (ČSÚ), reached 3.1% in September 2026 as a trend-cycle measure (more thoroughly adjusted for seasonal variations) compared with 3.2% in the previous month and 3.2% a year ago. In 2025, this average general unemployment rate, according to the CZSO survey, was 3%, and so far this year, its average level has reached 3.2%. Since 1993, this sample-based unemployment rate has ranged from a low of 2% in February 2019 to a high of 9.3% in January 2000.

Unemployment

(%)

CBA Monitor
You can hide a data set by clicking on the data set name in the chart legend.

Source of primary data

Czech Statistical Office (selection). Employment Office (registration)

Category

Economy

Data Frequency

monthly

Note

The general unemployment rate calculated by the Czech Statistical Office (ČSÚ) is derived from a sample survey of households living in apartments and is measured relative to the labor force (the sum of employed and unemployed individuals). The CZSO publishes a monthly time series for the 15–64 age group and—given the scope of the survey— —a more robust quarterly time series for both the 15–64 age group and those aged 15 and older, which is considered the main indicator of the sample unemployment rate.
In contrast, the unemployment rate calculated by the Labor Office compares the number of registered, available job seekers aged 15–64 to the total population in this age group.
Since May 2025, the Czech Statistical Office (ČSÚ) has been publishing the monthly unemployment rate in “trend-cycle” format instead of the previously published seasonally adjusted series, which it provides for quarterly surveys. The CZSO changed the calculation of the time series for data from 2018 onward, when it began incorporating demographic weights from the survey, as it conducts surveys only in private households. The Labor Office publishes unadjusted data, and their seasonal adjustment is an estimate by the Czech Banking Association (ČBA).

For download:

Comments

October Inflation Does Not Undermine the CNB’s Unconventional Communication Strategy

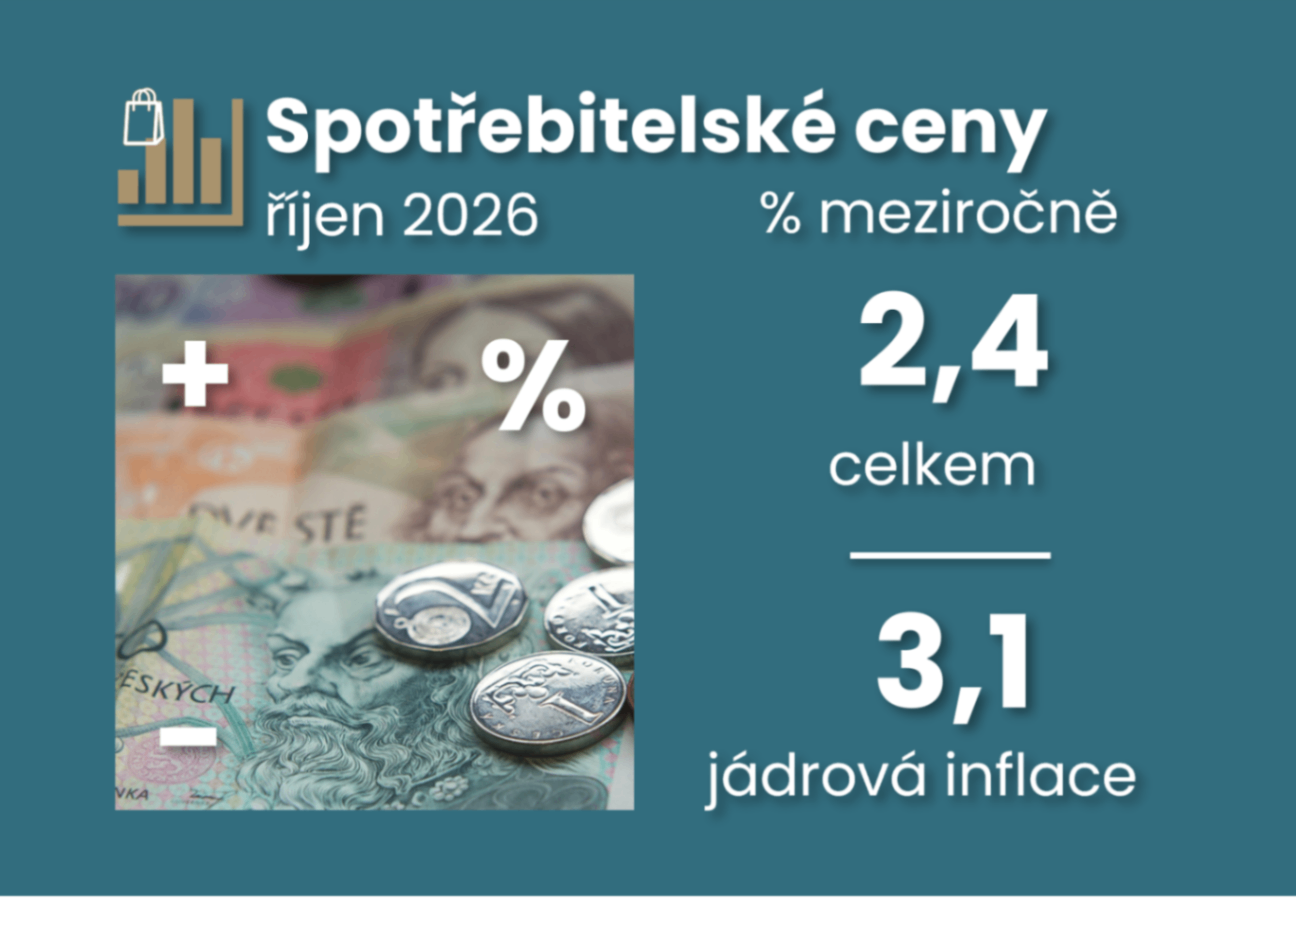
The detailed October inflation figures do not compel the CNB to change its proactive communication strategy, which was based on a close November vote (4 to 3) in favor of raising the interest rate to 4%. In my view, the CNB is using this communication to correct the financial market’s previous, more pronounced pricing in of a future interest rate hike. From the CNB’s perspective, market expectations appear to be influenced more by “beta”—that is, global factors (foreign interest rates and oil and gas prices)—than by “alpha”—that is, domestic factors (core inflation, the labor market, and fiscal policy). And since core inflation has remained at a year-over-year rate of 3.1% (constrasting to my initial estimate) it continues to allow the CNB to signal a more limited increase in interest rates. A closer look at core inflation reveals an interesting shift in its structure. These changes could undermine the CNB’s communication strategy, even though there are also supportive factors at play. Also important for the outlook on core inflation is the continued solid GDP growth without a significant recovery in productivity, as well as solid growth in industrial wages and core retail sales.

With core inflation rising by 3 percent, hawkish pressure on the CNB shows no signs of easing

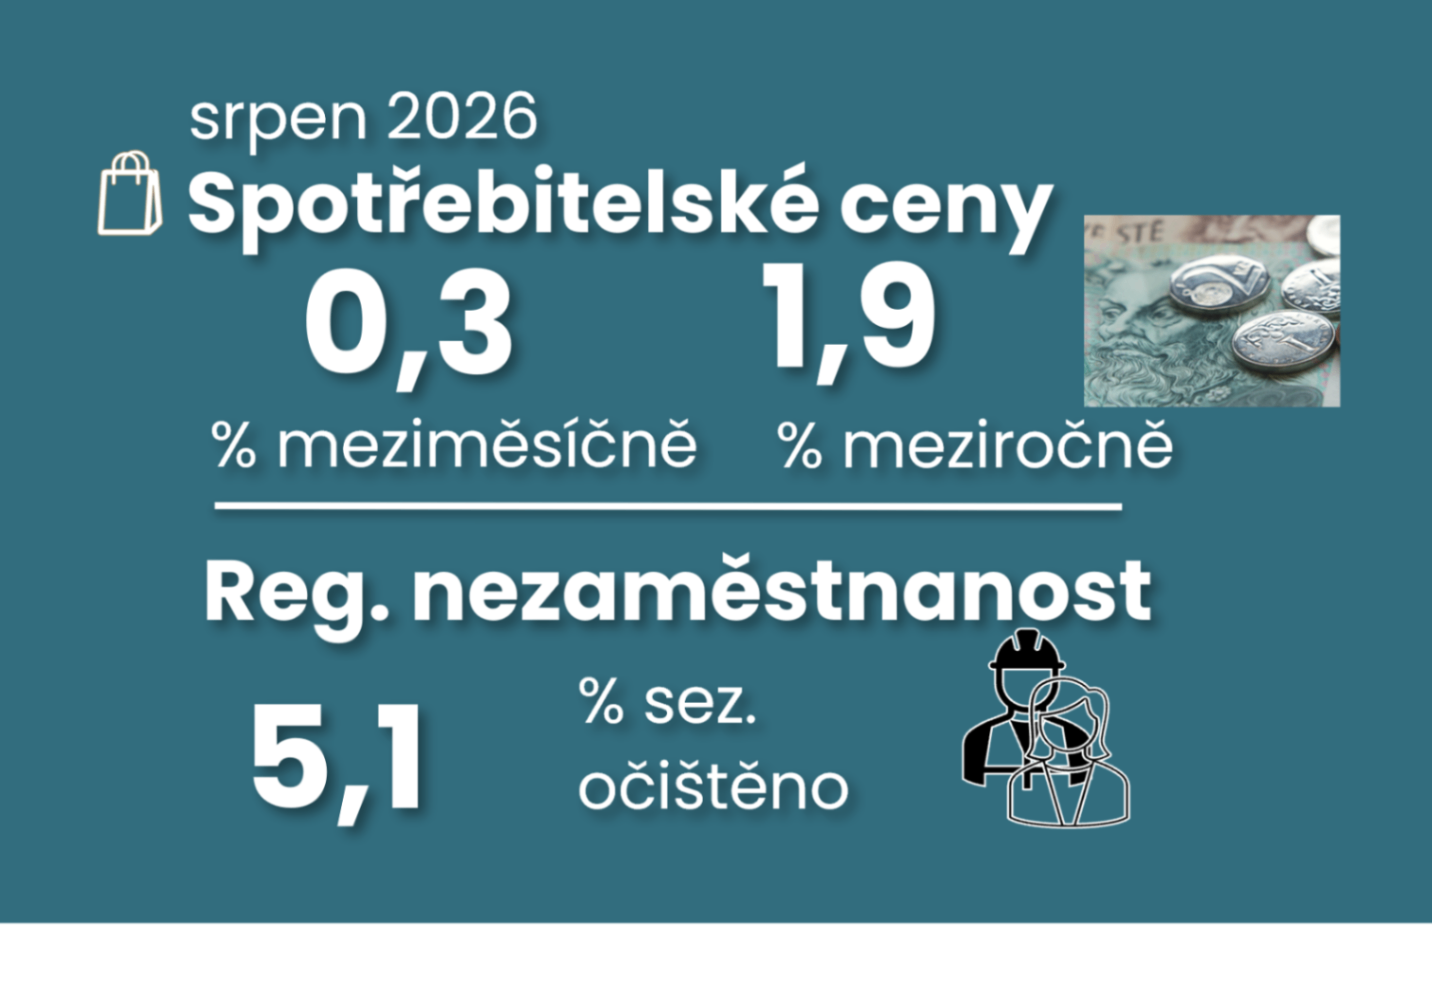
Inflation in August accelerated slightly to 1.9% year-over-year, but a more significant problem remains beneath the surface: core inflation remains at 3%, and service prices have accelerated again on a month-over-month basis. Labor market data point to a mild pro-inflationary risk rather than a disinflationary one. The CNB may leave interest rates unchanged at 3.75% in September and wait impatiently for the November forecast.

The Czech economy picked up slightly, but growth remained below the CNB's forecast

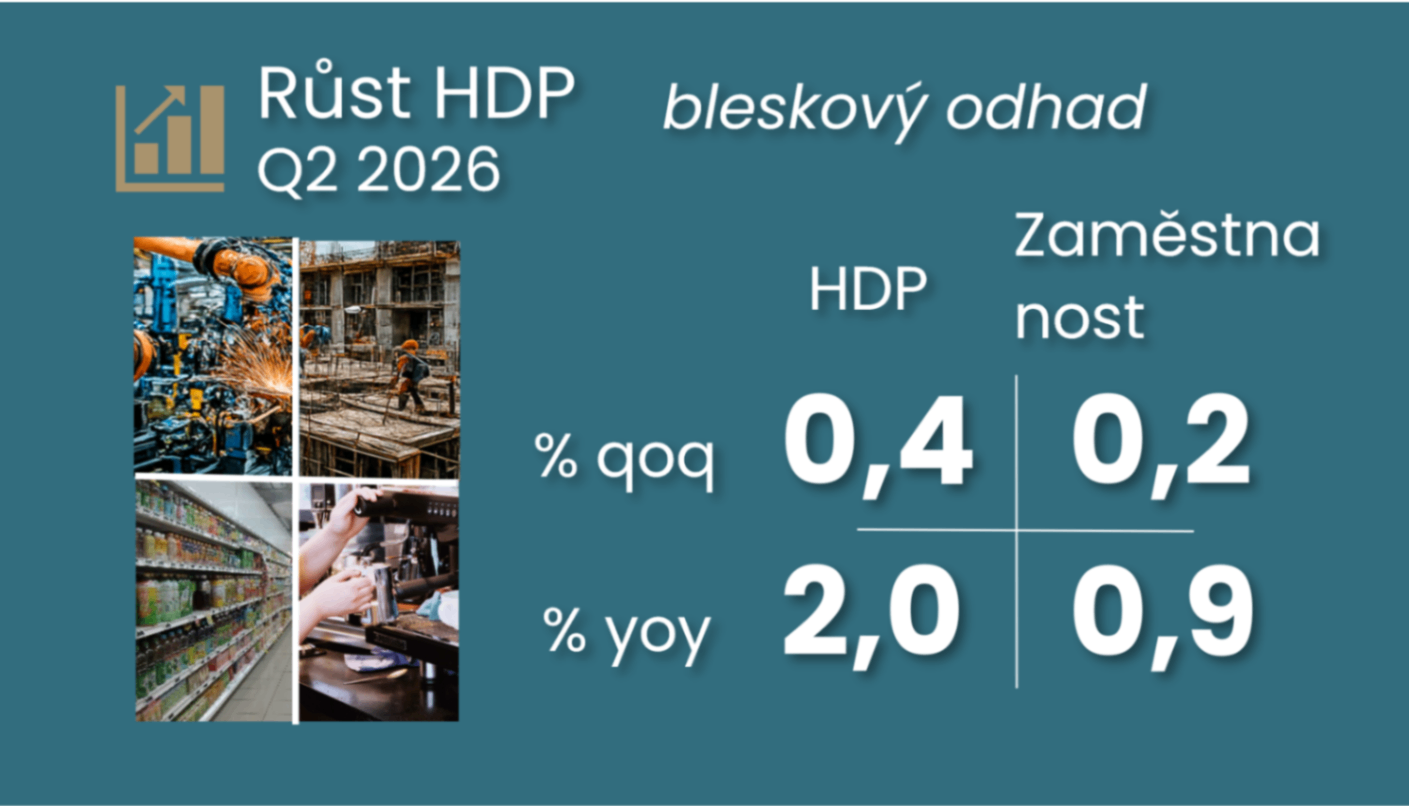
The Czech economy accelerated its quarter-over-quarter growth to 0.4% in the second quarter, up from 0.2% previously. The result was in line with the pace of growth across the entire eurozone but once again fell short of the CNB’s forecast, which may temper its hawkish stance. GDP growth in the second quarter was driven by household consumption and foreign trade, while investment activity held the economy back. The Czech Banking Association’s (CBA) forecast for the second half of the year anticipates only a slight further acceleration.

Slight economic slowdown in late 2025 and this year is poised to repeat last year's 2.5% growth

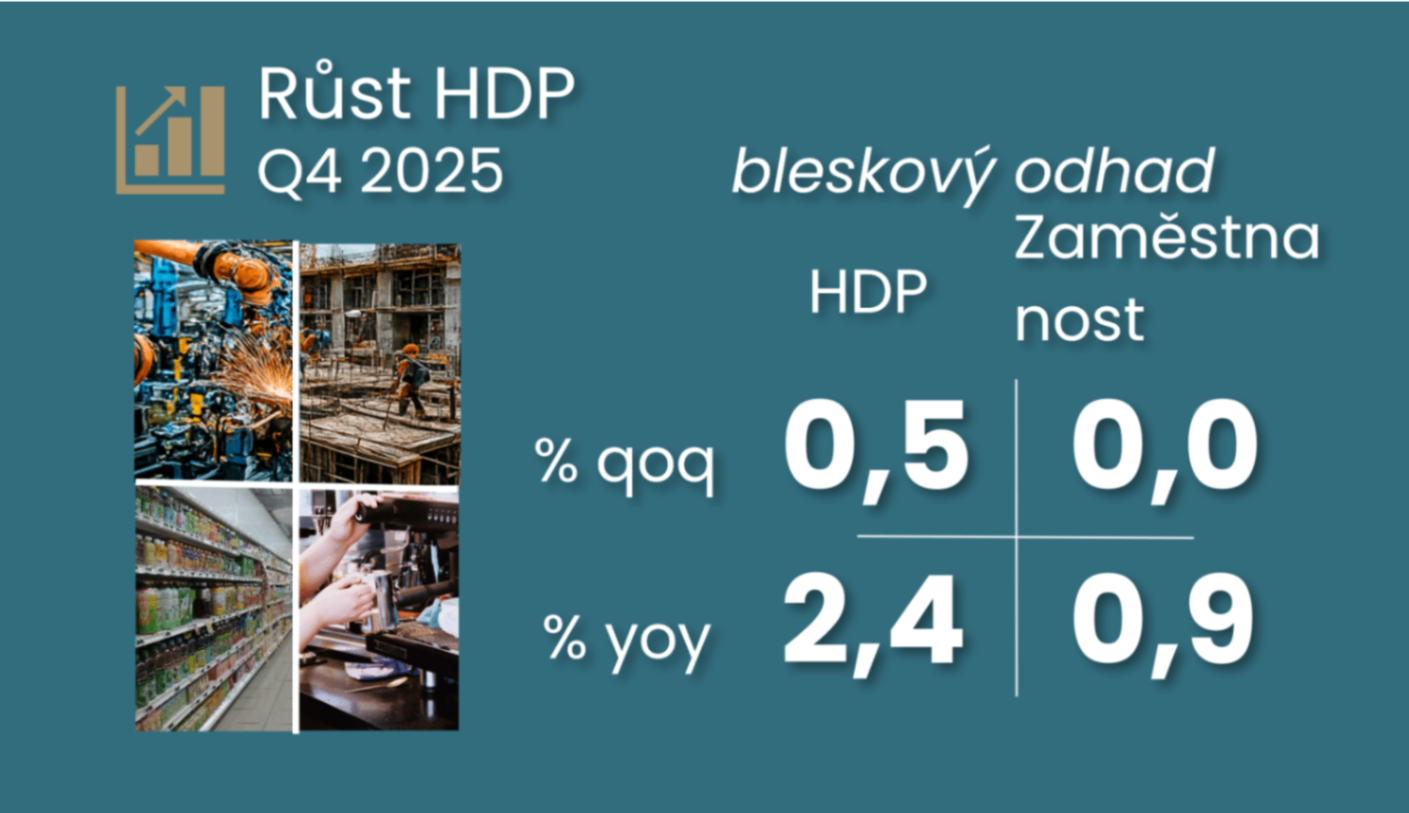
Comment by Jaromír Šindel, Chief Economist of the CBA: Economic growth slowed down at the end of last year, but still achieved solid 0.5% quarter-on-quarter GDP growth.The structure of growth has not changed significantly - consumption is dominant, which is probably not true of investment. This is in line with the latest sentiment data. A more positive sign is improving productivity. The outlook for this year is a repeat of last year's 2.5% growth, thanks to a better outlook for real wage growth and a change in fiscal policy. Conversely, weaker external demand, even given industrial sentiment, is likely to be a drag on stronger economic growth.

The Easing of November consumer inflation to 2.1% is not just about food

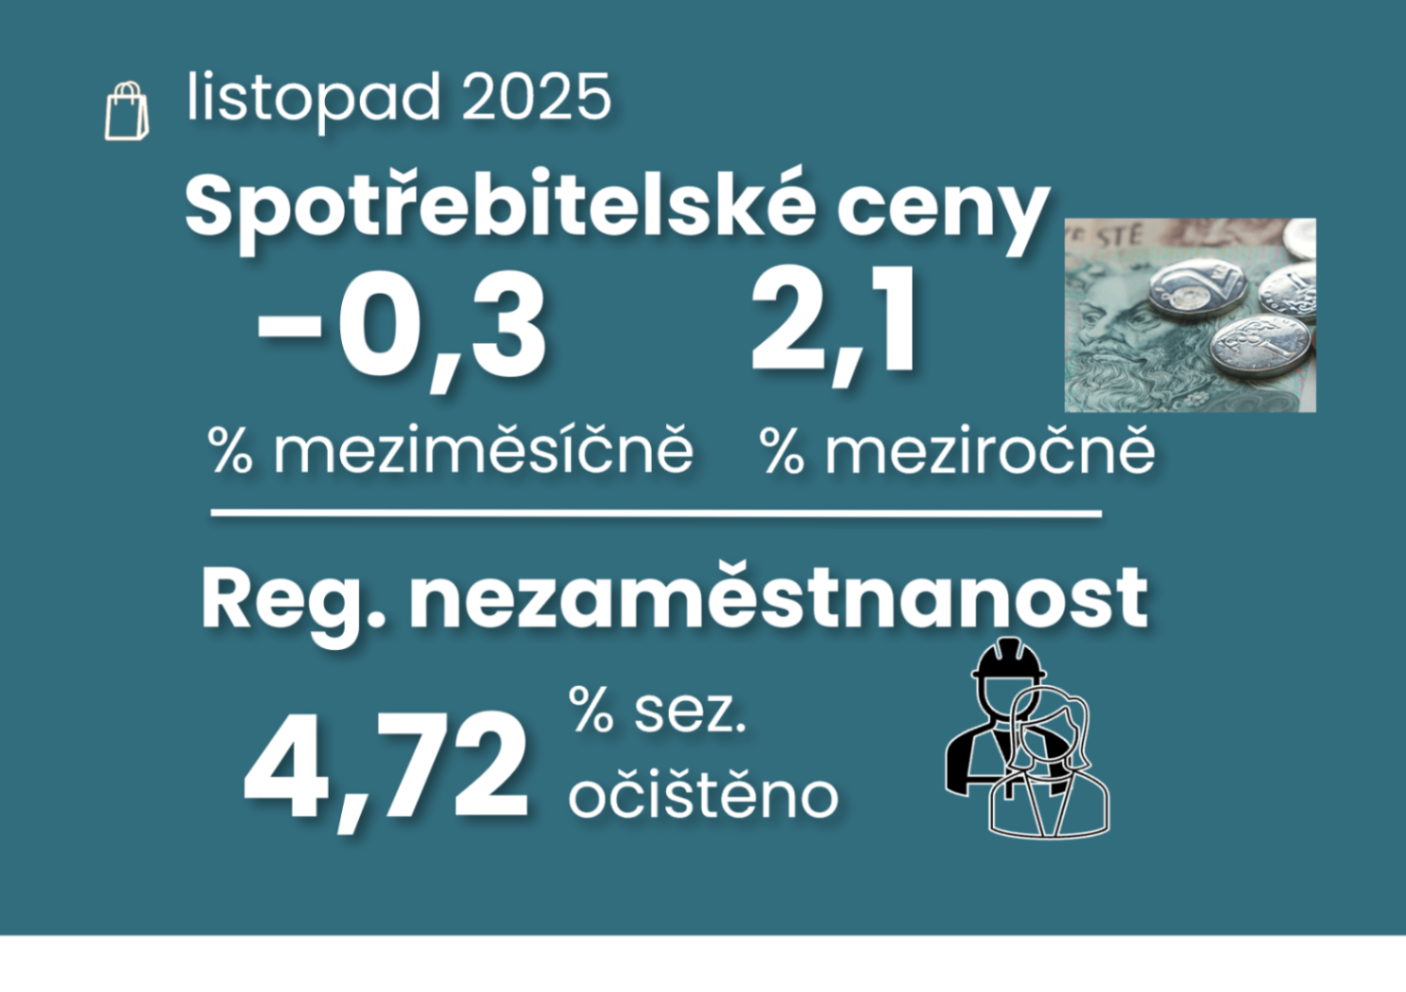
Comment by Jaromír Šindel, Chief Economist of the CBA: November consumer price growth did not slow to 2.1% year-on-year only thanks to volatile food prices, which were lower in November. The slowdown in core inflation to 2.6% was probably also due to lower prices for holidays, clothing, household furnishings, as well as lower prices in healthcare and energy. This, and November's move closer to the price inflation target for both headline and core inflation, eases hawkish pressures on the central bank. However, the continued brisk momentum in rent and food and other service prices will not allow the central bank to contemplate an interest rate cut.

October consumer inflation at 2.5% and continued rise in unemployment keep CNB on tenterhooks

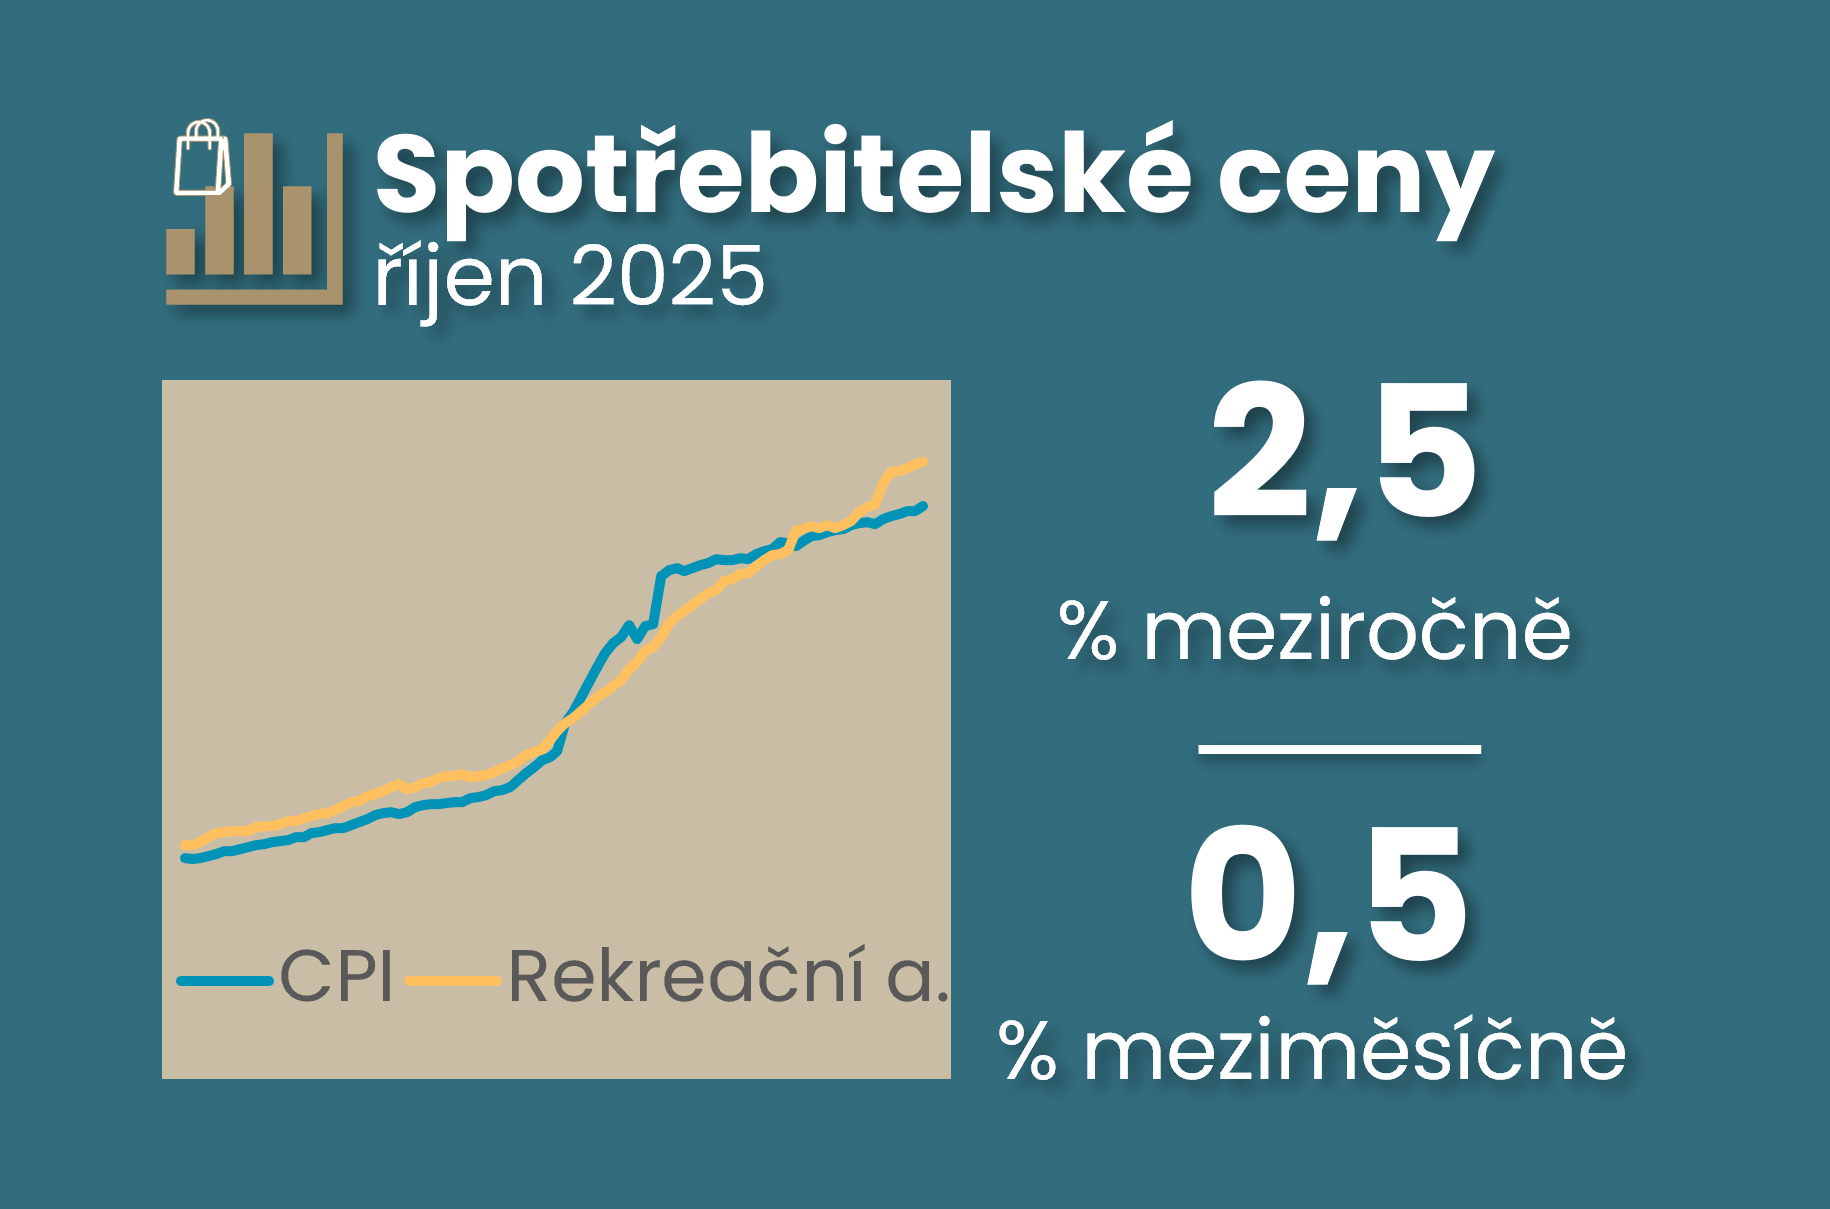
Comment by Jaromír Šindel, Chief Economist of the CBA: October consumer inflation not only confirmed a more pronounced shock from higher food prices, but also showed higher prices of transport services and prices of means of transport as part of core inflation. In the longer term, it is worth noting that imputed rental prices have already caught up with the previous inflation shock, and the same has been true for a few months for holiday prices. Thus, the higher October inflation and unemployment data will not help the central bank or the market resolve its dilemma of the next interest rate move.